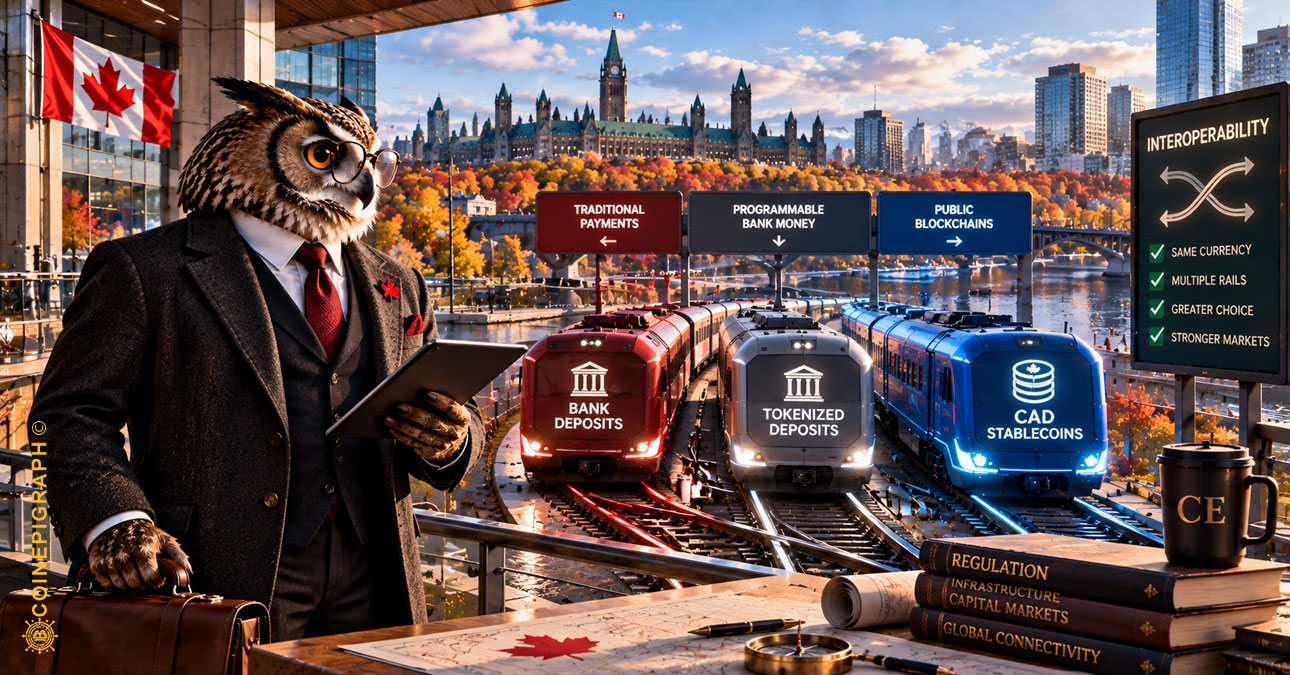
Six major banks are exploring tokenized deposits while a regulated Canadian-dollar stablecoin expands across public blockchains. The important question is no longer whether money becomes digital, but which form of digital money carries the deposit relationship, programmability and portability into the next financial system.
By CoinEpigraph Editorial Desk
Most Canadian dollars became digital a long time ago.
They appear as balances in bank accounts, move through electronic payment systems and rarely require physical currency to change hands. That makes the latest developments in Canada’s financial system easy to misread. The significance is not that the Canadian dollar is becoming digital.
It is that different forms of Canadian-dollar money are beginning to become programmable.
On September 22, six of Canada’s largest banks—BMO, CIBC, National Bank of Canada, RBC, Scotiabank and TD—announced that they are jointly exploring a tokenized-deposit system. The first phase would focus on moving tokenized deposits among Canadian financial institutions, with a longer-term objective of connecting the system to other emerging digital-asset initiatives. The banks say the project is intended to combine faster, programmable payments with the safety and regulatory oversight of the existing banking system.
One day later, another version of the Canadian dollar expanded in a different direction. Tetra Digital’s CADD stablecoin went live on Solana, adding the network to existing deployments on Ethereum, Base and Tempo. The Solana deployment was therefore not Canada’s selection of a national blockchain, nor was it the birth of CADD. It was the extension of an already existing regulated Canadian-dollar stablecoin across another public network.
Seen separately, these developments look like another collection of tokenization announcements.
Seen together, they raise a more interesting question.
What happens when commercial banks and blockchain networks begin creating different programmable representations of the same national currency?
The Deposit Is Becoming Programmable
A tokenized bank deposit is not simply another stablecoin.
The distinction begins with the liability.
Money held in a conventional commercial bank account represents a claim against the bank. Tokenizing that deposit does not inherently transform it into an independently issued digital currency. The underlying banking relationship can remain while the representation and movement of the deposit change.
That distinction matters because banks already possess something stablecoin issuers have spent years trying to approximate from outside the banking system: deeply embedded relationships with depositors, businesses, regulators, payment systems and credit markets.
Tokenization potentially gives that established monetary architecture a new capability.
The deposit can begin behaving more like software.
Payments can potentially become conditional. Settlement instructions can interact with digital assets. Transactions can be coordinated with other events. Financial applications can begin interacting with money through programmable interfaces rather than only through the traditional sequence of accounts, messages and reconciliation.
The Canadian banks have not disclosed enough technical detail to know precisely what architecture they will use, how settlement between institutions will ultimately occur, or how broadly the tokens could circulate. Their announcement should therefore be read as an exploration, not a completed national infrastructure project.
But one sentence deserves attention.
The banks say their longer-term objective is to connect tokenized deposits with other emerging digital-asset initiatives.
That moves the project beyond digitizing an existing payment process.
It opens the possibility of connecting commercial-bank money to an increasingly programmable financial environment.
Stablecoins Approach the Same Problem From the Other Direction
CADD begins somewhere else.
Rather than taking an existing commercial-bank deposit and making its representation programmable, the stablecoin creates a blockchain-native representation of Canadian-dollar value capable of circulating across supported networks.
Its addition of Solana attracted attention partly because the network offers a large existing digital-asset ecosystem. But treating this as evidence that Canada has “chosen Solana,” as suggested in the transcript circulating around the announcement, confuses an issuer’s infrastructure decision with national monetary policy. Pasted text
CADD now spans four networks.
That is more revealing.
The stablecoin model is naturally interested in portability. A digital Canadian dollar that can move through multiple blockchain environments can potentially reach wallets, applications, exchanges and financial protocols without requiring every participant to maintain the same traditional banking relationship.
The bank-deposit model begins with institutional integration and moves toward programmability.
The stablecoin model begins with programmability and attempts to build institutional integration around it.
Those trajectories are now approaching one another.
The Contest May Not Be Bank Money Versus Stablecoins
Financial innovation is often narrated as replacement.
Email replaced letters. Streaming displaced portions of physical media. Digital photography devastated film.
Money may prove less accommodating to that framework because different forms of money perform different institutional functions.
A bank deposit is not valuable merely because it transfers purchasing power. It sits inside a relationship involving deposits, lending, liquidity management, regulatory capital, deposit insurance and the broader creation of credit.
A stablecoin offers a different architecture. Its attraction can come from portability, continuous settlement, programmability and compatibility with digital markets.
Tokenized deposits introduce a third possibility: preserve much of the institutional structure of bank money while borrowing some of the technological properties associated with stablecoins.
The result does not necessarily have to be winner-take-all.
A business might hold operating cash as a bank deposit, use tokenized deposits for transactions within regulated financial networks and use stablecoins when interacting with particular blockchain applications or counter-parties.
What matters then is not which form of money eliminates the others.
It is how easily value can move between them.
That makes interoperability, rather than tokenization itself, one of the more consequential questions in Canada’s experiment.
The Monetary System Could Become Multi-Rail
The architecture becomes easier to understand if the Canadian dollar is separated from the infrastructure carrying it.
The currency is the unit of account.
The rail determines how the claim moves.
For decades, those two ideas were easy to mentally combine because commercial banks and established payment systems dominated the movement of national currencies. Blockchain infrastructure begins separating them.
A Canadian dollar can potentially travel as conventional commercial-bank money.
A claim denominated in Canadian dollars can travel as a tokenized bank deposit.
Canadian-dollar value can also circulate through a regulated stablecoin on a public blockchain.
The monetary unit can remain familiar while the transportation systems multiply.
That resembles something CoinEpigraph has observed elsewhere in the dollar system. Stablecoins do not necessarily require the disappearance of sovereign currencies. They can instead separate the currency from some of the infrastructure historically used to distribute it.
Tokenized deposits introduce the response from inside the banking perimeter.
The banks do not necessarily have to stop money from moving onto programmable infrastructure.
They can make bank money programmable too.
Canada May Be Building This While Its Financial Perimeter Expands
There is another reason the timing matters.
Days before the banks announced their tokenized-deposit initiative, Prime Minister Mark Carney proposed that Canada and Europe consider exploring an integrated market for financial services. He framed deeper integration as a way to broaden consumer choice, lower costs and improve companies’ access to capital while maintaining financial resilience.
The proposal remains just that—a proposal. It should not be confused with an agreement to merge Canadian and European financial markets.
But it places Canada’s digital-money experiments inside a broader discussion about financial connectivity.
If financial assets, deposits and payment instruments become increasingly programmable, cross-border integration becomes partly an infrastructure problem.
Which representations are recognized?
Which institutions may hold them?
Which networks can settle them?
How does identity travel across jurisdictions?
Which regulatory protections follow an asset when its technical representation moves?
And eventually, how easily can one regulated digital-money architecture communicate with another?
Those questions will matter considerably more than whether one country can claim leadership in a “crypto race.”
Then the Machines Arrive
There is also a less obvious connection to the emerging agentic economy.
Financial infrastructure is still largely designed around humans and institutions initiating transactions. AI agents complicate that architecture because software may increasingly be authorized to discover services, negotiate conditions and initiate payments within predetermined mandates.
That creates demand for money machines can interact with directly.
A Canadian AI agent might eventually encounter several forms of Canadian-dollar liquidity: conventional bank balances accessible through APIs, tokenized deposits operating inside regulated financial infrastructure, or stablecoins available through blockchain networks.
It would not necessarily have ideological preferences among them.
It could select according to transaction cost, settlement speed, liquidity, counter-party requirements, regulatory permissions and programmability.
That produces an intriguing possibility.
The next competition among payment rails may occur partly beyond human view.
Software could increasingly determine which rail best satisfies the economic instruction it has been given.
The machine may choose the money architecture transaction by transaction.
Tokenized Deposits Change the Stablecoin Question
For several years, the stablecoin debate has concentrated on whether digital dollars could pull activity or deposits away from banks.
Canada’s experiment suggests another possibility.
Banks can respond by changing the technological characteristics of the deposit itself.
That does not erase the competitive pressure stablecoins may create. Nor does it establish that tokenized deposits will achieve meaningful adoption. The Canadian project remains exploratory, its architecture is not fully disclosed, and the difficult work of interoperability, regulation and settlement still lies ahead.
But the direction is revealing.
The financial system may not divide neatly into old bank money on one side and new blockchain money on the other.
The boundary could become considerably less distinct.
Commercial-bank liabilities can become tokenized. Stablecoins can become increasingly regulated. Public blockchains can host institutional assets. Traditional financial institutions can interact with programmable networks. Eventually, several forms of money may coexist within applications that hide much of that complexity from the person—or machine—initiating the transaction.
Canada has not chosen the winning architecture.
It has begun experimenting with several of them at once.
That may ultimately prove more consequential.
The next stage of digital money may not be defined by the stablecoin replacing the bank deposit. It may be defined by the moment when the deposit, the stablecoin and the financial assets surrounding them all become programmable—and the financial system learns how to move value between them.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.