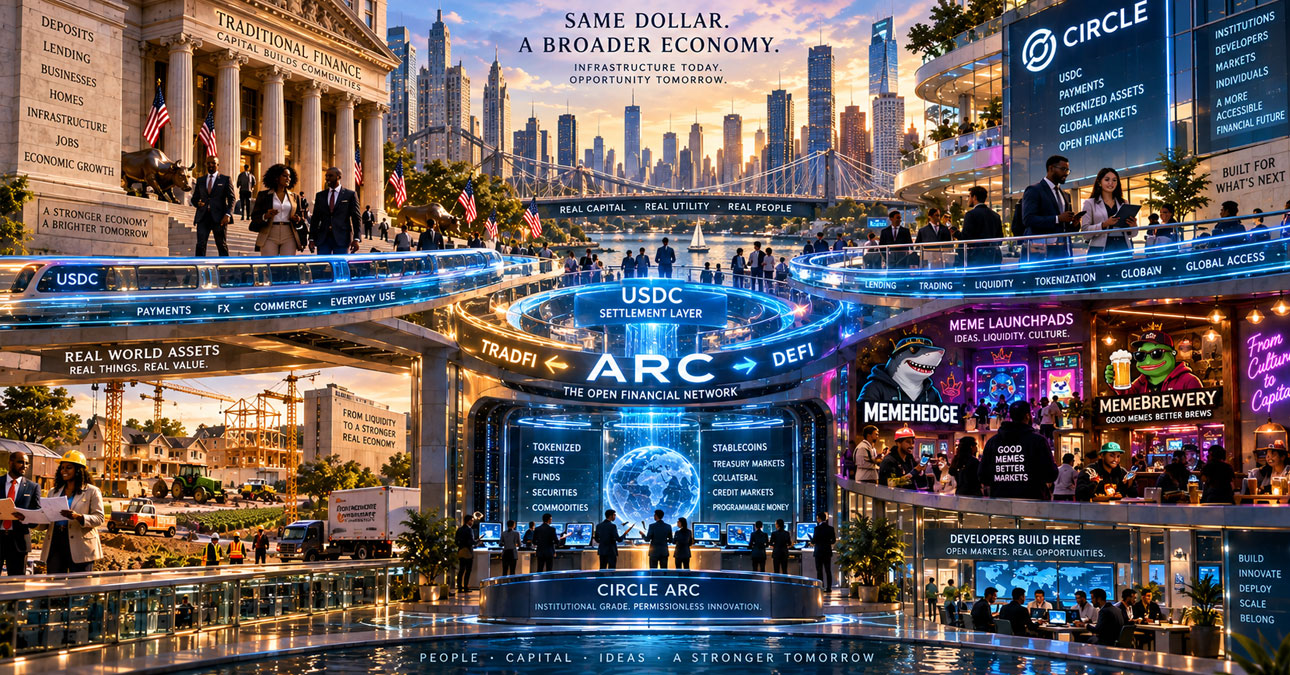
Circle launched Arc with BlackRock, DTCC, Visa and other institutions embedded in its infrastructure. Yet memecoin launchpads generated roughly 82% of the network’s first-day decentralized-exchange volume. The contradiction may reveal something more important than speculation: how open financial markets form when institutional infrastructure and permissionless capital occupy the same rails.
By CoinEpigraph Editorial Desk
Circle spent years building its position around a fairly straightforward proposition: if dollars and financial assets are going to move on public blockchains, the infrastructure underneath them will eventually have to satisfy institutions as well as crypto-native markets.
Arc is perhaps the clearest expression of that thesis yet.
The Layer 1 network went live publicly on September 16 with USDC used for transaction fees, sub-second finality, Ethereum-compatible tooling and a validator cohort that reads more like a cross-section of global financial infrastructure than a conventional blockchain project. BlackRock, DTCC, ICE, Mastercard, Visa, Standard Chartered and others are participating in network validation, while Aave, Morpho and Uniswap were among the applications available from launch. Circle says more than 100 institutional and ecosystem builders were involved at mainnet.
Then the market arrived.
During Arc’s first 24 hours, the network recorded approximately $410.8 million in decentralized-exchange volume across 7.76 million transactions. About $336.3 million of that DEX activity—roughly 82%—was attributed to 19 memecoin launchpads. Arguspad alone accounted for approximately $202.35 million and facilitated the creation of more than 83,000 tokens, according to onchain data reported from Dune.
For a network designed around stablecoin settlement, tokenized assets, payments, foreign exchange and institutional capital markets, it was an unusual opening act.
But it may not have been an irrelevant one.
The 82% Number Needs Context
The first distinction is important.
Memecoin launchpads did not account for 82% of all economic activity on Arc. They accounted for roughly 82% of reported DEX trading volume during the network’s first day.
Those are not interchangeable measurements.
Arc can support payments, stablecoin transfers, lending, collateral movement, foreign exchange, tokenized funds, cross-chain transfers and automated-agent transactions. Dune’s Arc integration tracks these activities separately. DEX volume captures one particularly visible part of the network, and trading volume itself measures turnover rather than unique capital. The same pool of liquidity can change hands repeatedly.
The remaining number is therefore worth noticing.
Removing the approximately $336.3 million associated with launchpads leaves about $74.6 million in non-launchpad DEX volume. That does not establish institutional adoption, but neither is it insignificant for the first day of a new blockchain.
The better question is not whether memes dominated Arc’s opening session. They did.
The question is what happens to the composition of activity after the opening session is over.
Arc Was Built Around a Different Market
Circle’s intended architecture is unusually explicit.
USDC serves as the network’s gas asset, allowing transaction fees to be denominated in dollars rather than a volatile native token. EURC and the tokenized Treasury product USYC were available at genesis. Arc was built for payments, foreign exchange, lending, treasury management and capital-market settlement.
BlackRock is expected to deploy BUIDL, its tokenized institutional liquidity fund, on Arc. DTCC is exploring tokenized asset settlement. Other institutional integrations involve custody, stablecoin access, foreign exchange and repo infrastructure. Aave and Morpho are supplying onchain credit architecture.
This is not the usual sequence in which a crypto network launches, attracts speculative liquidity and later attempts to persuade institutions that the infrastructure can support serious finance.
Circle has approached the problem from the other direction.
Much of the institutional architecture was standing there when the doors opened.
Yet Arc was also deliberately designed to accommodate open applications and permissionless innovation. Circle itself describes the network as an attempt to combine institutional-grade infrastructure with the composability associated with decentralized finance.
That combination explains why the first day’s activity matters.
The memecoins did not necessarily arrive in opposition to Arc’s architecture. They arrived because of it.
Permissionless Markets Move Faster Than Institutions
A bank, asset manager or securities infrastructure provider does not move capital onto a new financial network simply because the network is technically operational.
Institutional adoption carries custody requirements, compliance reviews, counterparty analysis, operational integration, risk limits, legal agreements and internal approvals. Even when the infrastructure works, capital migration takes time.
Permissionless markets face a radically different adoption curve.
A trader can connect a wallet.
A developer can deploy a contract.
A launchpad can create a market.
Liquidity can follow almost immediately.
This creates an asymmetry in the early life of open financial infrastructure. The participants with the lowest barriers to entry are capable of generating activity before participants with substantially larger pools of capital have completed the process required to participate.
Arc’s first day may therefore tell us less about what Arc ultimately becomes than about which form of capital can move fastest when new financial infrastructure becomes available.
That distinction matters.
If memecoin activity falls sharply while payments, credit, tokenized assets and non-launchpad liquidity continue expanding, the 82% figure will eventually look like an artifact of network formation rather than a description of Arc’s economic purpose.
If activity disappears with the speculation, the interpretation changes.
One day cannot resolve that question.
Speculation Can Also Test the Machinery
There is another mechanism worth watching.
Speculative markets are unusually effective at placing financial infrastructure under pressure.
They generate transactions quickly. They create new contracts. They demand liquidity, routing, wallet support and exchange execution. Participants respond immediately to differences in fees and settlement performance.
Circle had already conducted substantial technical testing before public launch. Arc’s testnet processed more than 700 million transactions, according to the company.
Public markets introduce a different test.
The participants are no longer following a controlled testing program. Real capital is moving according to economic incentives. Developers compete for attention. Traders exploit opportunities. Liquidity shifts. Infrastructure encounters behavior its designers do not necessarily coordinate.
That does not make speculative turnover economically equivalent to institutional settlement. It does mean that the same activity institutions may regard as peripheral can expose weaknesses in the infrastructure they may eventually use.
In that sense, Arc’s peculiar first day may have provided a public stress test alongside a speculative frenzy.
TradFi and DeFi Are Beginning to Occupy the Same Infrastructure
The more consequential observation is what sits underneath all of this.
For years, TradFi and DeFi have been described as competing financial systems.
Arc complicates that distinction.
Consider the participants operating across the network.
BlackRock can participate in validating infrastructure while tokenized investment products move onchain. DTCC can explore connections between conventional securities custody and tokenized markets. Visa and Mastercard can participate in network validation. Aave and Morpho can operate lending markets. Uniswap can provide decentralized trading. Wallet providers can give individuals direct access to those markets. And permissionless developers can deploy applications that none of those institutions designed.
The boundaries remain legally and economically important. A bank deposit is not a stablecoin. A tokenized security is still a security. A DeFi lending position does not become a bank loan merely because institutional participants share the underlying network.
But the infrastructure boundary is becoming less clean.
TradFi and DeFi no longer have to operate on separate rails in order to perform different functions.
That may ultimately prove more important than whether Arc’s first billion dollars of trading volume came from institutional assets or memecoins.
Liquidity Rarely Arrives in Its Final Form
Financial infrastructure does not always attract its eventual dominant use case first.
Early participants are often those most willing to tolerate unfamiliar technology, imperfect interfaces and uncertain market structure. Their activity helps create liquidity, tooling and operational experience that later participants can use without sharing the motivations of the early adopters.
Crypto has repeatedly demonstrated this pattern. Speculation has financed infrastructure that subsequently found applications in payments, stablecoins, tokenization and settlement.
Arc gives the mechanism an unusual institutional setting.
Circle did not build a speculative blockchain that now hopes to become financial infrastructure. It built financial infrastructure that immediately encountered permissionless speculation.
That inversion is worth watching.
The relevant measurement from here is not whether Arc can reproduce $410 million of daily DEX volume. It is whether the composition underneath that number changes.
Does non-launchpad trading deepen? Do USDC and EURC settlement flows grow? Does credit accumulate through Aave and Morpho? Does tokenized collateral begin moving between institutional and decentralized applications? Do BUIDL and other real-world assets develop meaningful onchain balances? Does payment and FX activity become large enough that DEX speculation becomes a smaller percentage of a much larger network?
Those numbers will tell us considerably more about Arc than its opening day did.
Circle has constructed an unusual experiment: a public financial network with institutions embedded in its operation, stablecoins embedded in its economics and permissionless applications embedded in its design.
The first participants to exploit that openness happened to be overwhelmingly speculative.
That is not yet evidence that Arc has succeeded in bringing institutional finance onchain. Nor does it establish that memecoin activity has somehow hijacked the network.
It demonstrates something narrower, but potentially more durable.
When institutional infrastructure becomes genuinely open, institutions do not necessarily determine who arrives first.
The rails can be built for one financial future while the market discovers another use for them immediately. What matters now is whether those uses remain separate—or begin supplying liquidity, infrastructure and market depth to the same emerging financial system.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.