France is not facing a sovereign funding crisis. It is confronting something slower and potentially more difficult: rising debt costs, weak growth and deteriorating public confidence are narrowing the government’s room to respond just as students, workers and citizens are demanding more from the state.
By CoinEpigraph Editorial Desk
France’s streets and its bond market are beginning to tell the same story.
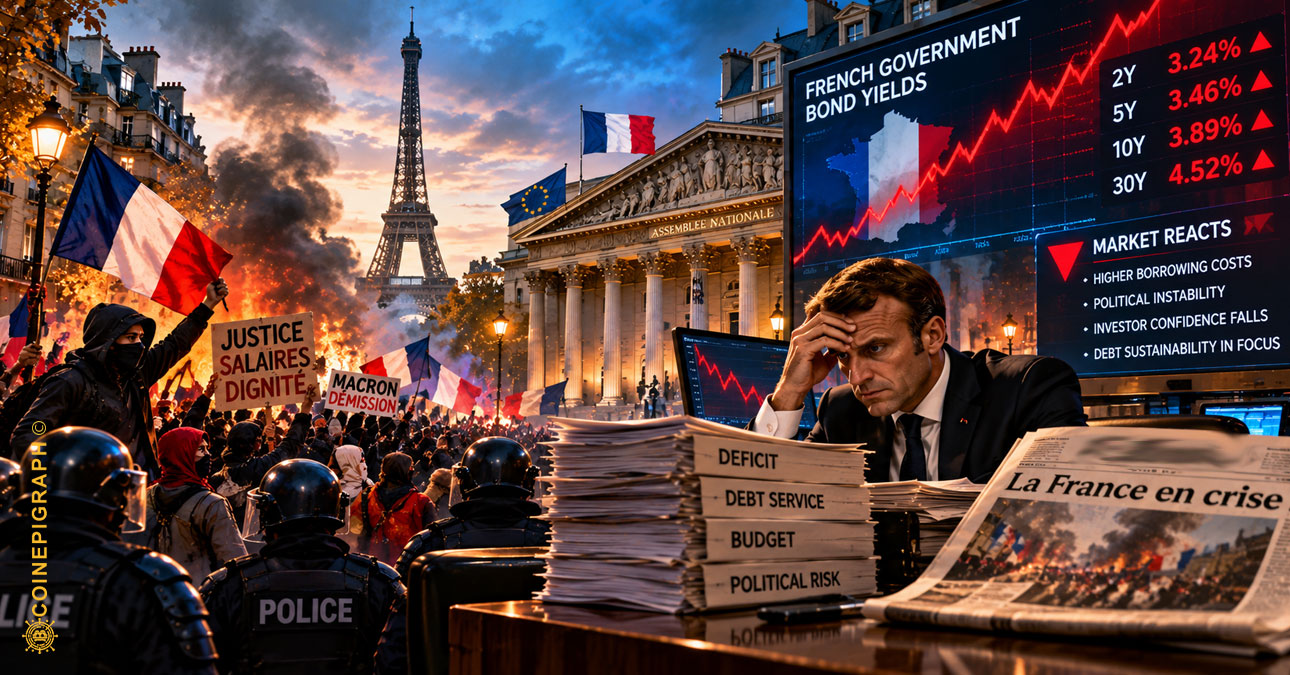
Nationwide demonstrations over living costs and declining public services erupted into some of the country’s worst civil unrest in years over the weekend. Looting, arson and attacks on public institutions accompanied broader protests involving students, workers and other citizens. The violence was not representative of everyone demonstrating, but its scale exposed something larger than a public-order problem: France is confronting rising demands on a state whose financial capacity to answer them is becoming increasingly constrained.
The financial numbers explain part of that constraint.
French public debt reached €3.596 trillion, or 119% of GDP, at the end of the second quarter, after standing at 117.5% only three months earlier. France expects a €311.7 billion state financing requirement this year and €339.7 billion in 2027. Debt-service costs are projected to rise from €62.6 billion this year to €72.9 billion next year.
None of this means France has lost access to capital markets.
Its debt auctions remain well subscribed. Through September, demand for medium- and long-term government securities was 2.5 times the amount offered. The International Monetary Fund continues to describe the French sovereign market as orderly, supported by a long maturity structure, diversified investors and ample banking-system liquidity.
France is not confronting a funding crisis.
It is confronting the rising cost of avoiding one.
The Debt Is Beginning to Reprice
The French 10-year government bond yield climbed to approximately 4.9% on October 19, while its spread over the German Bund widened to 146 basis points. Earlier this month, the French yield reached 4.99%, its highest level since 2002.
That does not mean France suddenly pays 4.9% on its entire debt stock.
Sovereign debt reprices gradually as existing bonds mature and new securities replace them. That process is already visible. The weighted-average yield on French medium- and long-term issuance has risen to 3.55% this year from 3.14% in 2025.
Next year’s financing requirement illustrates the mechanism.
France expects €19.4 billion of the increase in its 2027 funding needs to come from additional medium- and long-term securities reaching maturity, including borrowing undertaken during the pandemic and energy crises. France plans €340 billion of medium- and long-term issuance next year.
Old debt matures.
New debt replaces it.
The replacement becomes more expensive.
And yesterday’s fiscal choices begin occupying more of tomorrow’s budget.
The Other Side of the Balance Sheet Is in the Streets
That would be difficult enough if France were merely deciding how quickly to reduce a deficit.
It is not.
The government is attempting fiscal consolidation while portions of the population are demanding greater resources, better services and relief from rising living costs. Students and teachers have become part of a broader movement that increasingly overlaps with worker and union grievances. The weekend’s unrest widened the political consequences dramatically.
President Emmanuel Macron has now called for students, teachers, lawmakers, trade unions and business representatives to participate in discussions aimed at producing responses to the crisis.
The problem is that many of the grievances require precisely what France has less freedom to provide: money.
This is where deteriorating public infrastructure becomes part of the sovereign-debt story.
A government can reduce spending to improve its fiscal accounts. But if consolidation weakens schools, transportation, industrial infrastructure or other productive public assets, it can also damage the capacity needed to generate future growth.
Conversely, responding to every demand through additional borrowing can deepen the debt trajectory that markets are already beginning to price more aggressively.
France therefore faces an uncomfortable contradiction:
It needs to spend enough to restore confidence in the state while borrowing less to restore confidence in its finances.
Growth Was Supposed to Provide the Escape Route
There is another way to make a debt burden more manageable.
Grow the economy beneath it.
A larger productive economy generates additional income, employment and tax revenue while reducing the relative weight of existing debt. Productivity growth can therefore accomplish something austerity alone cannot: improve fiscal capacity while increasing the resources available to society.
But France is receiving little help from growth.
The IMF expects the French economy to expand only 0.4% in 2026 and 0.7% in 2027, compared with projected euro-area growth of 1.1% this year.
That matters because fiscal consolidation becomes substantially more difficult when the economy beneath the debt is barely expanding.
Taxes can be raised, but that can suppress investment and consumption.
Spending can be cut, but that can intensify political resistance and weaken public services.
Borrowing can continue, but higher yields gradually increase the cost.
And productive investment can be protected, but doing so requires governments to distinguish expenditures that expand future capacity from expenditures that merely preserve current commitments.
France increasingly has to make all of those choices simultaneously.
The Political Constraint Is Becoming a Financial Variable
This is where the weekend’s unrest enters the bond market.
Investors did not simply react to damaged buildings or television images of violence. They confronted what those events imply for the government’s ability to implement fiscal policy.
French bonds, equities and the euro weakened Monday as investors reassessed the political feasibility of deficit reduction. France’s 10-year yield jumped 13 basis points in a single session.
The connection is straightforward.
France needs fiscal reform.
Fiscal reform requires political consent or sufficient political authority to proceed without it.
Large-scale public resistance makes that adjustment harder.
If markets conclude that adjustment will be delayed, they can demand greater compensation for holding French debt.
Higher borrowing costs then make the required adjustment larger.
The political crisis can therefore feed the fiscal problem, while the fiscal problem restricts the government’s ability to resolve the political crisis.
That is the feedback loop now forming around France.
Markets Do Not Have to Stop Lending
The temptation will be to describe France as approaching a sovereign debt crisis.
The evidence does not support that conclusion.
France retains a large tax base, sophisticated financial institutions, substantial private wealth and access to the monetary architecture of the euro area. Its government securities continue attracting buyers. The IMF considers the increase in borrowing costs manageable in the near term.
But sovereign pressure does not begin only when investors refuse to lend.
It can begin when investors continue lending at prices that increasingly influence government choices.
France’s spread over Germany is now effectively attaching a market price to French political and fiscal uncertainty. The longer elevated yields persist, the more that price migrates from trading screens into actual government interest expense.
That changes the meaning of fiscal sovereignty.
A government may remain entirely capable of financing itself while discovering that maintaining market confidence increasingly determines what it can promise voters, workers, pensioners, students and public institutions.
France Is Being Squeezed From Both Directions
France still has options.
It can reform spending, alter taxation, improve labor participation, encourage investment and protect expenditures capable of raising productivity. It can also attempt to rebuild enough political consensus to make those changes durable.
What it cannot do is eliminate the accumulated obligations already sitting on its balance sheet.
Nor can it ignore the population now demanding that the state deliver more.
That leaves France facing two constituencies whose demands increasingly move in opposite directions.
Citizens are effectively saying:
The state must do more.
The sovereign bond market is effectively saying:
The state must demonstrate that it can afford what it already does.
Neither controls France.
But the space between them is narrowing.
France’s immediate danger is therefore not that investors suddenly stop financing the Republic. It is that debt service, political fragmentation and public dissatisfaction gradually consume the government’s ability to choose its own priorities.
A sovereign funding crisis would be dramatic.
What France is experiencing may be more incremental: the conversion of accumulated debt into political constraint.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.