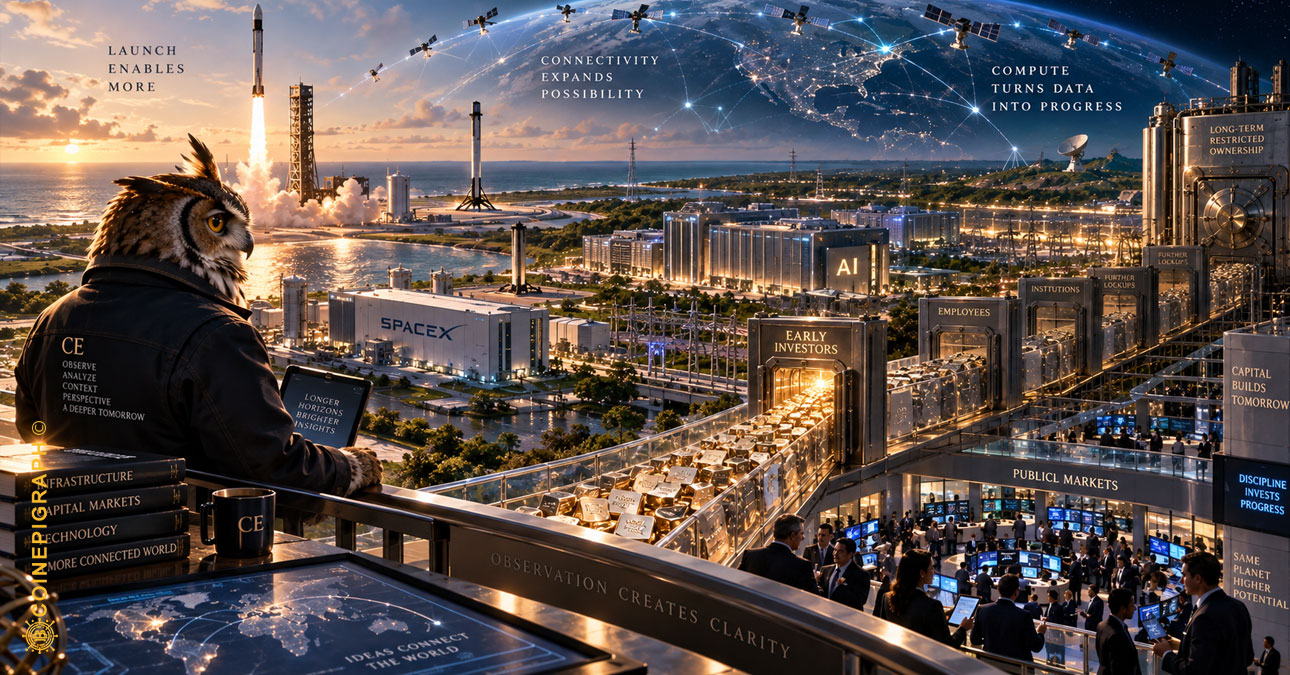
The public market is trying to price something it has rarely encountered: launch infrastructure, orbital communications and artificial intelligence operating inside a single capital system. At the same time, SpaceX’s IPO is converting two decades of private-market appreciation into public liquidity. The question is no longer simply what SpaceX is worth. It is what kind of company investors are actually being asked to value.
By CoinEpigraph Editorial Desk
SpaceX entered the public market carrying an unusual problem.
It was already enormous.
By the time the company completed its June IPO, much of the difficult work normally associated with early public ownership had already occurred somewhere else. Rockets had been developed. Reusability had been demonstrated. Starlink had become a global communications network. Employees, founders and venture investors had spent years holding equity while the company accumulated capabilities and private-market value.
The public market did not finance SpaceX from infancy.
It inherited the result.
That distinction is becoming increasingly important as investors attempt to interpret the company’s first months of public trading. SpaceX’s shares initially surged from their $135 offering price, briefly reaching $225.64, before retreating sharply. The temptation is to read that movement as a referendum on the company’s prospects.
It may be considerably more complicated.
SpaceX is undergoing two forms of price discovery simultaneously. The market is trying to determine the value of an increasingly integrated infrastructure company while the supply of equity available to express that judgment is itself changing dramatically.
One is a valuation problem.
The other is a liquidity event twenty years in the making.
The Aerospace Company Is Disappearing
SpaceX still builds rockets, but describing it simply as an aerospace company now obscures more than it explains.
Its economic architecture increasingly connects three large systems: launch, connectivity and artificial intelligence.
The first relationship is already well established. SpaceX manufactures launch vehicles, uses them to deploy its own satellites, and operates the network those satellites create. Starlink turns what would otherwise be episodic launch economics into recurring connectivity revenue.
By the end of June, Starlink had approximately 12 million subscribers, double the year-earlier level. Consumer average revenue per user, however, had fallen from about $85 to $66 as the network expanded into lower-priced international markets.
That combination tells us something important. Starlink is no longer merely proving demand. It is beginning to confront the economics of becoming global infrastructure.
The next layer is much newer.
SpaceX reported $7.8 billion of second-quarter revenue, up roughly 92% year over year. Its AI segment generated approximately $2.6 billion while Connectivity produced $4.3 billion. Connectivity operating income reached roughly $1.7 billion.
The company that once needed enormous amounts of capital to build a satellite network now owns a satellite network capable of generating operating profits while SpaceX finances its next generation of capital-intensive systems.
That changes the analytical frame.
The Infrastructure Flywheel
Traditional conglomerates generally place several businesses beneath a common corporate parent. Their value often depends upon whether diversification produces enough financial benefit to compensate investors for organizational complexity.
SpaceX is attempting something different.
Its businesses can potentially become inputs into one another.
Rockets deploy satellites. Satellites create connectivity. Connectivity generates recurring cash flow. Starship, if it achieves reliable commercial scale, could change the cost and volume of putting substantially larger infrastructure into orbit. AI introduces another enormous consumer of computing, communications, energy and eventually perhaps orbital capacity.
The structure begins to resemble an infrastructure flywheel:
launch capacity → orbital capacity → connectivity → recurring cash flow → compute infrastructure → additional demand for launch and communications
That is not simply diversification.
It is vertical integration across physical and computational infrastructure.
And that distinction could eventually deserve a valuation premium if ownership of one layer materially lowers the cost, increases the scale or accelerates development of another.
The danger is that the same mechanism works in reverse.
When several layers require extraordinary investment simultaneously, vertical integration can compound capital intensity just as effectively as it compounds competitive advantage.
$18.4 Billion Changes the Conversation
SpaceX’s second-quarter capital expenditure makes that tension difficult to ignore.
The company spent approximately $18.4 billion in a single quarter, including roughly $15.8 billion on AI compute infrastructure. SpaceX ended the quarter with approximately 1.4 gigawatts of nameplate compute capacity and expects more than 2 gigawatts by year-end.
The scale matters beyond SpaceX.
Across the broader market, enthusiasm surrounding AI infrastructure is beginning to encounter harder questions about construction delays, electricity availability, financing conditions and the timing of returns. Reuters Breakingviews notes that AI-related debt issuance had approached $500 billion through early August as lenders simultaneously began demanding stronger protections around infrastructure projects.
SpaceX therefore occupies an unusual position.
Starlink demonstrates that the company can spend aggressively on infrastructure for years and eventually create a recurring-revenue network. But the success of one capital cycle does not guarantee the economics of the next.
The market must decide whether AI represents another Starlink—or merely another enormous claimant on Starlink’s success.
That is the capital-allocation question beneath the technology story.
Then There Is the Other Supply Problem
Capital expenditure is only one form of supply SpaceX investors must absorb.
The other is shares.
Approximately 639 million shares entered public hands through the IPO. On August 6, another 911.5 million shares became eligible for trading, more than doubling the potential supply. Additional staggered releases are designed to continue increasing the float; Reuters reported that roughly 40% of the company could become tradable by December, compared with less than 5% immediately after the IPO. Musk’s stake and other restricted holdings remain locked substantially longer.
That means SpaceX’s early trading history cannot be interpreted without considering scarcity.
When enormous investor demand encounters a tiny public float, price discovery occurs against an artificially narrow supply of shares. As restrictions expire, the market isn’t merely changing its opinion about the company.
The quantity of SpaceX available for the market to price is changing.
Enterprise-value discovery and float normalization are happening at the same time.
That makes the next distinction even more important.
The IPO Did Not Create the Wealth. It Created the Exit.
Early SpaceX investors face an entirely different calculation from someone buying SPCX today.
A new investor must decide whether a company already valued in the neighborhood of $2 trillion can generate sufficient future earnings and cash flows to justify further appreciation.
An employee or venture investor who acquired shares years earlier may be solving a portfolio-management problem instead.
Those shareholders can remain convinced that SpaceX has an extraordinary future and still sell.
They may need diversification. A venture fund may need distributions. Employees may have accumulated a disproportionate percentage of their personal wealth in one company. Institutions may encounter concentration limits. Families that have waited a decade or longer may simply decide that some portion of extraordinary paper appreciation should become permanent capital.
The unlocking of shares therefore creates a signal that markets must interpret carefully.
Selling does not necessarily mean deteriorating conviction.
Sometimes it means the investment worked.
The unusual SpaceX lockup structure reinforces the point. Most restricted shares were subject to a nominal 180-day restriction, but the prospectus incorporated multiple early-release provisions, while Musk and certain significant holders received a 366-day restriction without those early-release provisions.
The staged structure changes the shape of potential selling pressure rather than eliminating it.
And what the public market is gradually absorbing is not merely additional stock.
It is years of private-market appreciation becoming liquid.
That may prove to be one of the most important features of the SpaceX IPO.
The public offering did not create the wealth embedded in those shares. It created a market capable of realizing it.
Public Capital Without Public Control
There is another asymmetry.
SpaceX has become public without adopting the conventional assumption that economic ownership should translate proportionally into corporate influence.
Its governance architecture uses unequal voting rights and other mechanisms that leave Musk and insiders with extraordinary control. Reuters recently cited SpaceX as part of a broader shift in which public investors have demonstrated increasing willingness to surrender governance influence when purchasing access to founder-controlled companies.
That effectively asks public shareholders to make another wager.
They are not simply buying SpaceX’s assets and future cash flows. They are accepting that much of the capital-allocation authority governing those assets remains concentrated elsewhere.
For investors who believe the integration of rockets, satellites, communications and AI depends upon unusually long-duration founder control, that may be a feature.
For investors concerned about capital discipline, related strategic ambitions or governance accountability, it is a risk.
Both can be true.
What Deserves to Be Multiplied?
This leaves conventional valuation with an uncomfortable problem.
SpaceX can be approached as an aerospace company, but that undervalues Starlink.
It can be modeled as a telecommunications company, but that misses the launch infrastructure making the network possible.
AI can be valued separately, but doing so may ignore how compute could eventually interact with SpaceX’s communications and orbital systems.
A sum-of-the-parts valuation captures the businesses individually but risks missing the economic value created by their integration.
And simply awarding an enormous conglomerate premium assumes the flywheel will work before its economics have been proven.
That is why SpaceX may be testing something larger than its own valuation.
It may be testing whether public markets will recognize vertically integrated infrastructure itself as an investable category—a system in which ownership of transportation, communications and computation creates value precisely because those layers no longer need to be purchased independently from one another.
The answer will not be determined by whether Starship flies, Starlink adds another million subscribers or AI revenue grows in a particular quarter.
It will be determined by whether those systems ultimately make one another more economically valuable than they would have been separately.
Until then, SpaceX’s public market is conducting two experiments at once.
One is determining how much investors should pay for an infrastructure architecture that has few obvious public-market comparisons.
The other is discovering how much of two decades of privately accumulated wealth the public market can absorb as that ownership progressively becomes liquid.
The first determines what SpaceX might eventually be worth.
The second may determine what its shares trade for while the market figures it out.
And that leaves investors with a valuation question considerably more difficult than choosing the right revenue multiple:
SpaceX’s problem is not merely determining what number should be multiplied. It is determining what, exactly, deserves to be multiplied at all.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.