BlackRock sees artificial intelligence and digital assets converging as autonomous software begins to transact, purchase services and eventually procure its own compute. The deeper transition may come when machines move from processing economic information to exercising economic authority.
By CoinEpigraph Editorial Desk
For most of the digital economy, machines have executed instructions while humans remained somewhere near the beginning of the economic decision.
Software could route an order, settle a trade, reconcile a payment or allocate computing resources. Automation made those processes faster, but it generally did not change who decided that the transaction should happen. Somewhere upstream, a person or institution established the intent.
Artificial intelligence is beginning to complicate that distinction.
In The Machine-Native Economy, BlackRock argues that two technological systems that largely developed on separate tracks are beginning to converge. Artificial intelligence represents what the firm calls machine-native intelligence. Digital assets can provide machine-native money and machine-readable economic claims. Agentic AI connects the two by giving software increasing ability to plan and execute multistep tasks through external systems with limited human intervention.
The proposition is larger than AI discovering crypto.
If software can increasingly decide what resources it needs, compare alternatives and initiate transactions, the financial system begins confronting a different kind of participant.
The question is no longer simply how machines process financial information.
It is how machines are permitted to act economically.
From Machine-Readable Information to Machine-Readable Value
BlackRock begins with an architectural analogy.
Large language models divide human language into tokens that can be numerically processed. Blockchains perform a technically different function, but tokenization can represent cash, securities, fund interests and other economic claims in standardized digital forms that software can inspect and transfer.
The comparison should not be stretched beyond its usefulness. An LLM token is not economically or technically equivalent to a tokenized security.
What matters is machine readability.
Financial assets traditionally sit behind layers of databases, account structures, intermediaries and proprietary interfaces. Tokenization can expose portions of that architecture through standardized transaction fields and programmable rules. An authorized agent can potentially inspect balances and conditions, initiate a transaction and verify settlement without navigating the same collection of bespoke integrations that characterize much of legacy finance.
That extends a progression already underway across capital markets.
Tokenization makes an asset digitally portable. Smart contracts can make portions of its behavior programmable. Agentic AI introduces another possibility: the entity interacting with that asset can itself become increasingly autonomous.
That is not merely another stage of financial automation.
It changes where economic intent can originate.
When Software Needs to Spend
Consider an ordinary travel request.
A user tells an AI agent to arrange a trip within a particular budget. The agent may need to access a calendar, obtain airfare and hotel information, coordinate with specialized agents, purchase data and eventually complete reservations.
BlackRock uses essentially this example to illustrate an emerging stack involving Anthropic’s Model Context Protocol, Google’s Agent2Agent protocol, Coinbase’s x402 and payment systems being developed by Stripe, OpenAI, Google and Visa. Some components connect agents with information. Others allow agents to communicate. Still others provide ways to establish authorization or settle transactions.
Traditional payments do not disappear from this architecture.
BlackRock specifically expects modified conventional systems to remain important when agents transact with human-operated businesses and consumers. But machine-to-machine commerce can create requirements for which existing infrastructure was not primarily designed: extremely small payments, continuous availability, programmable execution and rapid verifiable settlement.
That is where stablecoins become more interesting than the familiar argument about faster payments.
BlackRock reports more than $300 billion of stablecoins in circulation as of September 2026 and more than $11 trillion of adjusted stablecoin transaction volume during 2025. It also cautions that comparisons with card networks are imperfect, while noting that the same stablecoin volume remained well below the $93 trillion transferred through ACH.
The more consequential distinction is architectural.
An AI agent purchasing an API call or a small increment of compute does not necessarily need a financial relationship designed around a human entering payment credentials. It needs an accepted unit of account, permission to spend it and a mechanism through which the counterparty can determine that settlement occurred.
The dollar can remain familiar even as the transaction environment becomes machine-native.
The Harder Problem Is Authority
This is where the machine-native economy becomes more difficult than machine-native payments.
Giving software the technical ability to transfer money is relatively straightforward. Determining when it is authorized to do so is another problem entirely.
BlackRock’s own architecture already points toward this distinction. KYC, AML and know-your-agent checks may occur outside the blockchain, with verified results passed onchain to determine transaction eligibility. Google’s AP2 uses cryptographic mandates and audit trails to provide evidence of user authorization. Visa’s Trusted Agent Protocol is intended to help merchants distinguish trusted agents receiving payment credentials.
The accompanying industry discussion pushes the problem further, emphasizing persistent agent identity, portability between financial environments and limits on delegated authority. The important insight is not its advocacy for any particular blockchain. It is the recognition that an agent acting economically on someone’s behalf requires more than a wallet.
A useful architecture begins to emerge:
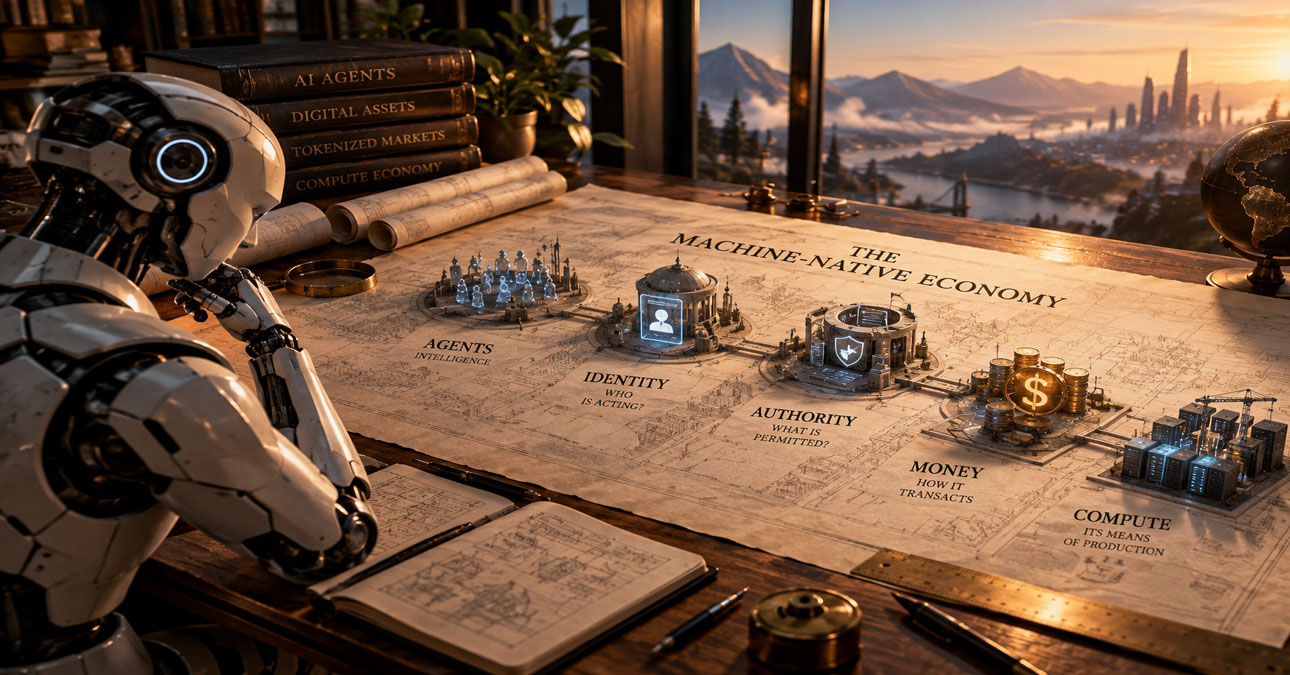
Intelligence → Identity → Authority → Settlement
Intelligence allows the machine to determine what action may be useful.
Identity allows counterparties and systems to establish what is acting.
Authority establishes what the agent is permitted to do.
Settlement executes the resulting economic instruction.
The third layer may ultimately be the most difficult.
An agent authorized to spend $100 purchasing data has not necessarily been authorized to borrow $100,000. Permission to rebalance a portfolio does not necessarily imply permission to liquidate it. Authorization valid for an hour should not silently become authority that persists indefinitely.
Machine autonomy therefore requires boundaries that machines themselves can interpret.
That suggests a larger infrastructure problem:
Giving a machine money is relatively easy. Giving a machine authority without surrendering control may be much harder.
Verification Does Not Eliminate Judgment
Blockchain infrastructure can provide another important property: auditability.
A network can establish that a transaction occurred, that the appropriate signature authorized it at the protocol level and that the resulting state became final.
But settlement cannot establish that the economic decision itself was correct.
A blockchain might prove that an AI agent paid a compute provider. It cannot, through settlement alone, prove that the provider accurately described its capacity, that an external dataset contained reliable information or that the model interpreted the information correctly before deciding to purchase.
That leaves a boundary between transaction validity and decision validity.
As machines assume greater economic discretion, identity, provenance, reputation and accountability become part of the financial architecture surrounding settlement.
The machine-native economy will therefore require more than machines that can pay.
It will require systems capable of determining what machines are allowed to believe, access and do—and mechanisms for assigning responsibility when those decisions go wrong.
There May Be More Than One Machine-Native Financial System
This also argues against assuming that agentic finance inevitably resolves onto one blockchain or even entirely onto public blockchains.
BlackRock is considerably more careful.
Its framework includes both blockchain-native protocols and adaptations of traditional payment infrastructure. It describes x402 as blockchain-agnostic, discusses stablecoin settlement across multiple networks and recognizes systems such as Stripe’s Machine Payments Protocol that can settle through stablecoins or traditional payment methods.
The eventual architecture could therefore be heterogeneous.
Some consumer transactions may remain on card rails. Regulated institutional activity may continue through banking infrastructure. Stablecoins may dominate particular categories of programmable dollar settlement. Public blockchains could become important where composability, open settlement or neutrality matter. Permissioned systems may remain attractive where confidentiality and controlled participation are paramount.
The machine-native economy does not require one machine-native financial system.
Machines may instead learn to route economic activity across multiple systems according to cost, speed, permissions, liquidity and legal requirements.
That possibility is more consequential than a competition over which blockchain wins.
The agent may eventually choose the rail.
Compute Could Become a Financial Market
BlackRock then moves from the money machines might spend to the resource they increasingly consume.
Compute.
The scale is potentially enormous. Estimates cited in the paper put cumulative AI capital expenditure above $5 trillion between 2025 and 2030, while consensus estimates for the major cloud businesses of Amazon, Microsoft and Google imply approximately $1.1 trillion of combined revenue by 2030. These are projections rather than outcomes, but they illustrate the potential size of the economic resource being constructed beneath AI.
BlackRock asks what happens if claims on computing capacity themselves become standardized enough to trade.
That begins to resemble the development of a commodity market.
The analogy is imperfect but useful. Commodity markets required standards describing grade, quantity, location, delivery and settlement before heterogeneous physical resources could support deep financial markets.
Compute has similar problems.
An hour of one GPU generation is not equivalent to an hour of another. Electricity costs vary geographically. Latency matters. Location matters. Hardware specialization matters. Delivery guarantees matter.
BlackRock explicitly acknowledges these contract-design and market-structure difficulties. It nevertheless sees precedent in basis markets, contracts for difference and other mechanisms developed around heterogeneous commodities. Standardized compute claims could eventually be transferred, pledged as collateral and settled through programmable infrastructure. Exchange-traded compute futures could potentially emerge around sufficiently standardized units.
Before that market can become deep, finance must answer a deceptively difficult question:
What exactly is the standardized economic unit being traded?
Solve that problem and a familiar progression becomes possible.
Compute capacity becomes measurable. Measurable capacity becomes contractible. Contracts become tradable. Tradable claims become financeable. Standardized claims can potentially become collateral.
The physical infrastructure beneath artificial intelligence begins acquiring financial infrastructure of its own.
The Machine Could Eventually Procure Its Own Means of Production
This is where the two halves of BlackRock’s argument meet.
An autonomous agent could estimate the computing resources required to perform a task, query marketplaces for available capacity, compare price, performance, latency, location and hardware specialization, provision the appropriate resources and pay for them programmatically.
BlackRock describes precisely this kind of workflow and points to Stripe’s agreement to acquire OpenRouter—which distributes workloads among hundreds of AI models—as an early indication that model routing, compute optimization, payments and usage-based billing may begin moving closer together. BlackRock nevertheless stresses that agentic payment activity remains nascent.
The economic loop is striking.
AI interprets information.
The agent determines what it needs.
Markets expose resources in machine-readable form.
The agent selects compute.
Programmable money settles the purchase.
Compute performs the work.
The agent continues operating.
At that point, software is doing something fundamentally different from executing a human instruction.
It is beginning to procure the productive resources required to accomplish its mandate.
The Value-Capture Question Remains Unsettled
None of this establishes that every blockchain—or every cryptoasset—benefits.
BlackRock is unusually disciplined on this point.
Where stablecoin transactions occur on permissionless networks, increased activity could create additional demand for blockspace and validator services. But whether that activity produces economic value for the network’s native asset depends on fee design, staking economics, gas sponsorship and other network-specific mechanisms.
The distinction is fundamental:
Infrastructure adoption and token value capture are not the same mechanism.
A machine-native economy could generate extraordinary economic activity while value accumulates somewhere entirely different from the blockchain token investors expected to capture it.
Stablecoin issuers could capture part of it.
AI platforms could capture part.
Compute providers could capture part.
Identity and authorization systems could capture part.
Payment orchestrators, data providers, validators, marketplaces and applications could capture other portions.
Competition could also commoditize significant pieces of the stack.
The investment question is therefore not merely whether machines transact onchain.
It is where the economics accumulate when they do.
When Economic Authority Becomes Programmable
The progression now extends beyond AI and blockchain.
Financial assets are becoming machine-readable.
Money is becoming programmable.
Markets are becoming increasingly software-defined.
Compute may become contractible and financeable.
And intelligent software is acquiring greater capacity to decide how those resources should be used.
The next step is more consequential because it concerns authority itself.
For centuries, financial infrastructure has ultimately been organized around people and institutions capable of owning property, entering agreements, assuming liabilities and accepting responsibility for decisions.
Agentic systems do not fit neatly into that architecture.
They can act without necessarily possessing legal personhood. They can execute without necessarily bearing liability. They can make increasingly sophisticated decisions while remaining subject to authority delegated by someone else.
The machine-native economy therefore cannot be understood simply as a payment upgrade.
It is the beginning of an infrastructure problem involving intelligence, identity, authority, ownership, verification and settlement at the same time.
BlackRock has identified an important convergence: machines that can interpret the world are approaching financial infrastructure through which they can act upon it.
The harder problem begins after that connection is made.
The financial system will have to determine not merely whether a machine can transact, but what it may decide, what it may purchase, what it may control—and where responsibility returns when the machine reaches the boundary of its authority.
Machine-native money may provide the rails.
Programmable authority may determine how far the machines are allowed to travel.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.