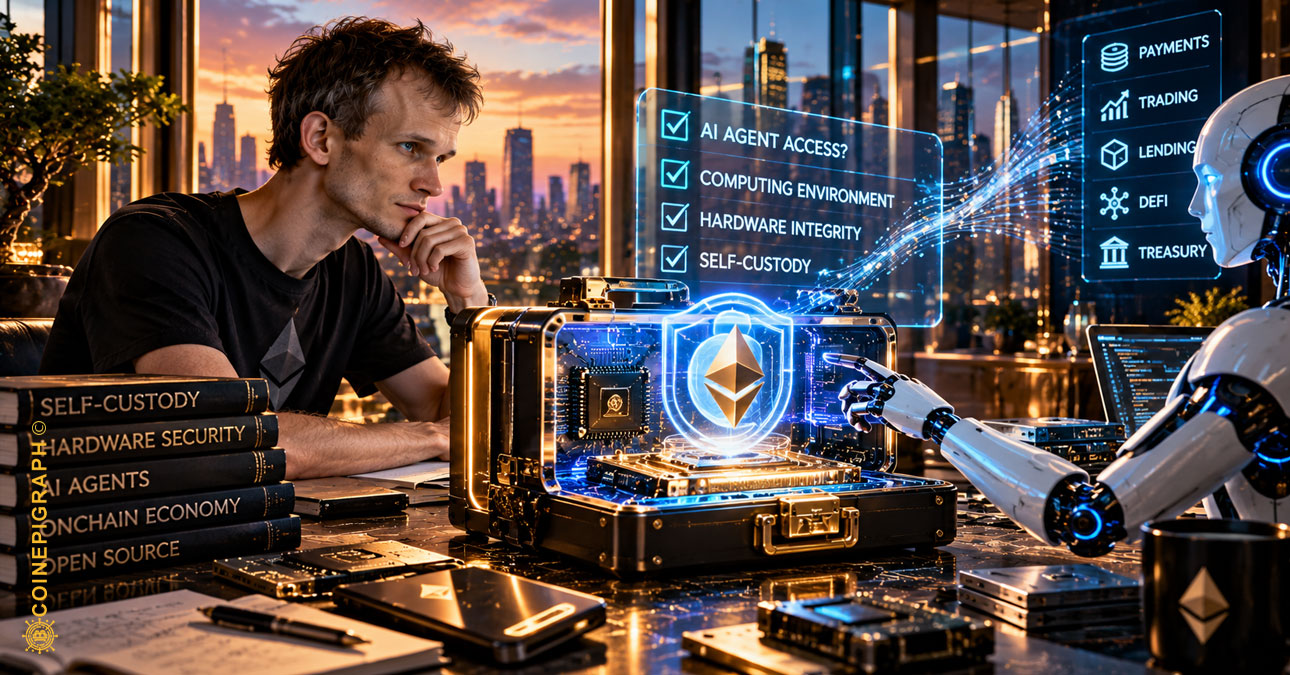
Ethereum co-founder Vitalik Buterin is extending the familiar principle of self-custody beyond private keys and into the hardware that protects them. As AI agents begin exercising financial authority, the question of who controls the computing environment may become as important as who owns the assets.
By CoinEpigraph Editorial Desk
For more than a decade, cryptocurrency ownership has rested upon a relatively straightforward principle: whoever controls the private keys controls the ability to authorize transactions.
That principle helped distinguish blockchain-based assets from conventional financial accounts. Rather than relying entirely upon a bank or custodian to recognize ownership and execute instructions, individuals could hold cryptographic credentials capable of authorizing transactions directly.
But the simplicity of that arrangement concealed a dependency. Private keys do not operate independently of the machines that store, protect and use them.
At the OKX NOW conference in Singapore on October 6, Ethereum co-founder Vitalik Buterin suggested that the industry’s familiar maxim, “Not your keys, not your coins,” may eventually become “Not your silicon, not your keys.”
His observation came within a broader discussion of artificial intelligence, programmable data and the security challenges emerging as AI agents begin interacting directly with blockchain networks. Buterin argued that protecting digital systems increasingly requires examining the entire computing environment, including the hardware upon which software depends.
The implication reaches beyond cryptocurrency wallets. As financial institutions tokenize assets and autonomous software acquires greater responsibility for managing them, cryptographic ownership may increasingly depend upon infrastructure whose security cannot be established by a valid digital signature alone.
The Difference Between a Valid Signature and an Authorized Decision
Blockchain networks are particularly effective at verifying cryptographic conditions.
When a transaction is submitted, the network can determine whether the required signatures are valid and whether the transaction satisfies the protocol’s rules. Those assurances are essential to the operation of decentralized financial systems.
They do not necessarily establish that the person controlling the assets intended the transaction.
A compromised operating system might alter a destination address before signing. Malicious wallet software could misrepresent transaction details. An attacker with access to an institutional signing environment might produce a technically valid authorization that violates the organization’s intended controls.
In each case, the blockchain could function exactly as designed while the owner’s economic intentions are defeated.
This distinction becomes increasingly important as digital assets move beyond individually managed wallets.
Institutional custody frequently involves multiple authorization layers, specialized signing devices, operational policies and software systems connecting portfolio managers with settlement infrastructure. The security of the private key remains essential, but so does the integrity of every component capable of influencing how that key is used.
The question is therefore changing from whether a signature is valid to whether the process producing that signature can be trusted.
AI Is Expanding the Authorization Perimeter
Artificial intelligence introduces another layer between financial ownership and transaction execution.
Buterin described a future in which AI agents increasingly replace conventional application interfaces. Rather than navigating a website, selecting an asset and manually approving each interaction, users could instruct an agent to perform complex operations on their behalf.
He offered an example from his own experience: using a locally running AI agent to generate a script that updated his Ethereum Name Service information without relying on a traditional interface.
That approach could reduce certain vulnerabilities associated with compromised websites and malicious frontends. Yet Buterin also identified new risks, including prompt injection and AI systems misunderstanding the transactions they have been instructed to perform.
For institutional finance, the consequences are substantial.
An autonomous agent might monitor collateral positions, rebalance tokenized portfolios, execute trades or interact with decentralized lending protocols. Those activities could improve efficiency by reducing the need for continuous human intervention.
They also require institutions to distinguish between the authority delegated to an agent and the actions the agent is technically capable of performing.
Consider an agent authorized to rebalance a portfolio within established risk limits.
If its operating environment is compromised, an attacker might manipulate the information it receives or redirect its instructions. The resulting transaction could still carry a valid signature from an authorized wallet.
The failure would not necessarily occur in the blockchain’s cryptography. It could occur in the software responsible for interpreting instructions and deciding when authorization should be exercised.
That is why agent-based financial systems will require controls beyond key management. Spending limits, transaction simulation, independent policy enforcement, restricted permissions and mechanisms for revoking authority become part of the security architecture.
AI does not invalidate cryptographic ownership. It expands the environment that must remain trustworthy for that ownership to be exercised safely.
Decentralized Finance Still Depends on Physical Infrastructure
Buterin’s reference to silicon introduces a second institutional consideration: the relationship between decentralized financial networks and concentrated computing infrastructure.
Blockchain networks can distribute transaction validation across independent participants. Their users, however, still depend upon processors, operating systems, secure elements, firmware and communications infrastructure manufactured or maintained by identifiable organizations.
A decentralized ledger does not eliminate those dependencies.
Hardware wallets illustrate the distinction. Their purpose is to isolate sensitive cryptographic operations from less trusted computing environments. But the protections they provide still depend upon hardware design, firmware integrity, implementation quality and the security of the device’s manufacturing and distribution processes.
Physical possession alone cannot establish that every component is trustworthy.
The same issue becomes more consequential inside institutional custody operations, where hardware security modules and specialized computing environments may protect assets belonging to numerous clients.
These technologies can provide substantial safeguards. They can also create dependencies upon proprietary systems whose internal operation may not be independently inspectable by every customer.
The resulting question is not whether financial institutions should abandon commercial hardware. Modern finance could not function without it.
It is whether the institutions relying upon that hardware possess sufficient means to verify its integrity, constrain its authority and recover when a trusted component fails.
Decentralization at the ledger level does not automatically produce operational independence at the computing level.
That distinction may become increasingly important as tokenized financial markets expand.
The Emerging Economics of Trusted Execution
The security requirements of digital finance could also influence where economic value accumulates.
Traditional financial institutions have long paid for custody, auditing, transaction monitoring and operational risk management. As assets become programmable, portions of those functions are moving into software and specialized hardware.
A similar development may emerge around trusted execution.
Hardware security modules, secure computing environments, independently verifiable firmware and transaction-policy systems could become more important components of institutional financial infrastructure.
Their commercial value would arise from the ability to establish that sensitive operations occurred within defined security conditions.
This does not mean every institution will need to manufacture its own processors or abandon proprietary technology. Nor does open-source hardware automatically guarantee security. A publicly inspectable design can still contain vulnerabilities, and the manufactured device must still correspond to the design that was examined.
The more consequential development would be a shift toward systems whose behavior can be independently assessed rather than accepted solely through contractual assurances.
That introduces a familiar financial-market tension.
Institutions seeking greater independence from traditional intermediaries may become dependent upon a different set of technology providers. Semiconductor manufacturers, cloud infrastructure operators and security vendors could acquire influence over the systems responsible for exercising financial authority.
The economic benefits of decentralization would then coexist with concentrated dependencies elsewhere in the computing stack.
Tokenization Raises the Stakes
The importance of this problem grows as blockchain infrastructure begins representing assets beyond cryptocurrencies.
Tokenized securities, investment funds, deposits and real-world assets introduce legal and operational relationships that cannot be resolved through cryptographic signatures alone.
A token may represent a claim against an issuer, a custodial arrangement or an entitlement governed by contractual terms. Its transfer can be technically valid while the underlying transaction remains subject to legal restrictions, institutional approvals or other obligations.
The systems authorizing those transfers must therefore operate within both technical and institutional boundaries.
As more financial activity becomes automated, the integrity of the computing environment will influence whether those boundaries can be enforced reliably.
A compromised agent managing tokenized collateral, for example, could create consequences extending beyond the immediate movement of tokens. Unauthorized transfers might affect financing arrangements, margin requirements and the obligations of other market participants.
That makes trusted execution a market-structure concern rather than merely a wallet-security feature.
The challenge is to preserve the efficiencies of programmable finance without allowing automation to weaken the controls that make financial authority accountable.
Ownership Is Becoming a Question of Governable Infrastructure
The original self-custody movement addressed a genuine weakness in conventional finance: individuals often depended upon intermediaries to recognize and exercise their property rights.
Blockchain technology introduced an alternative in which cryptographic credentials could provide direct transaction authority.
But direct authority and dependable control are not identical.
A private key establishes the ability to authorize a transaction. The surrounding computing environment determines how that ability is protected, presented and exercised.
As AI agents become more capable, institutions will increasingly need to govern not only the credentials used to move assets but also the software making decisions and the hardware enforcing those decisions.
This may produce stronger demand for verifiable computing, independent security controls and architectures that separate transaction preparation from final authorization.
It may also change how institutions evaluate digital custody providers. The quality of their controls could depend as much upon the integrity of execution environments and the enforceability of authorization policies as upon the cryptographic methods protecting private keys.
Buterin’s silicon formulation captures that transition without requiring the conclusion that existing wallets are fundamentally insecure.
The blockchain industry has spent years demonstrating that ownership and transfers can be verified without relying upon a single financial intermediary. The arrival of increasingly autonomous financial systems extends the challenge into the machinery responsible for exercising those rights.
Blockchain made ownership cryptographically verifiable. The next challenge is making the computing infrastructure that exercises financial authority sufficiently transparent, constrained and accountable to preserve the intentions of those who own the assets.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.