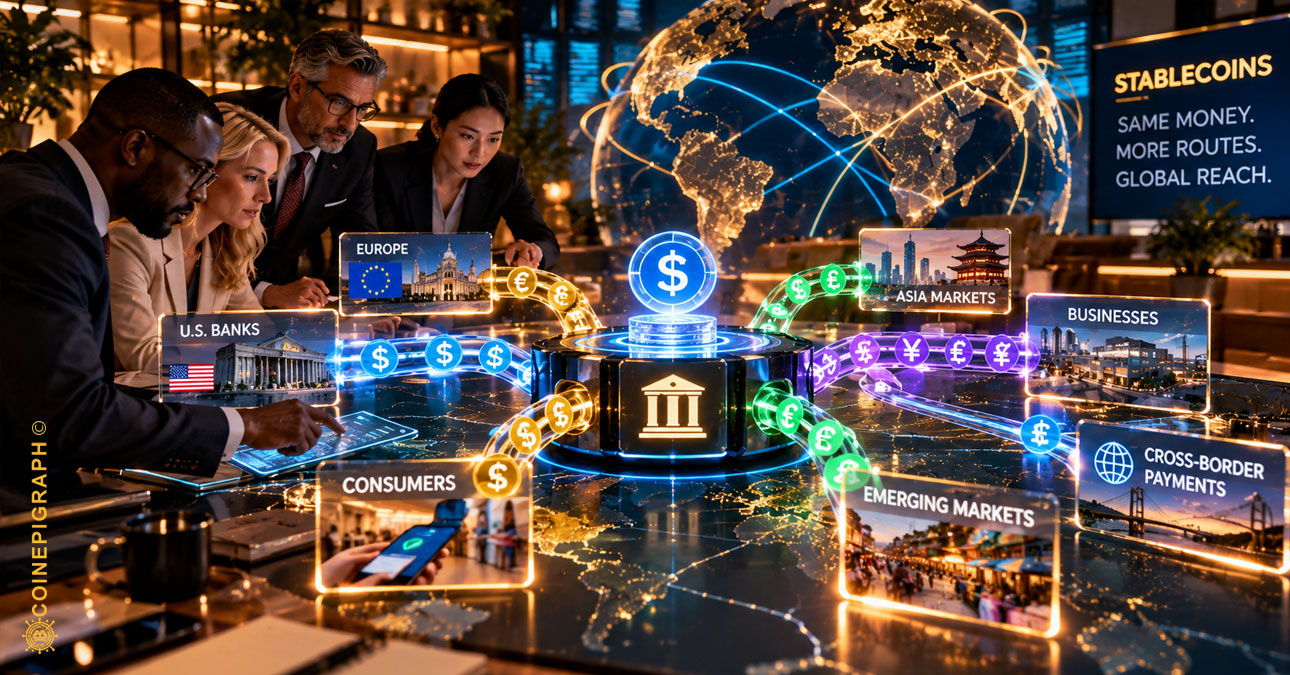
The emergence of bank-backed stablecoins, tokenized deposits, and programmable settlement networks suggests that the next contest in digital finance may not be over which form of money prevails, but who controls the infrastructure connecting them.
By CoinEpigraph Editorial Desk
The financial industry has spent much of the past decade debating what digital money should become. Stablecoins offered a privately issued, blockchain-native alternative to conventional payment infrastructure. Central bank digital currencies promised a sovereign version of programmable money. Tokenized deposits emerged as a way for commercial banks to modernize their liabilities without surrendering the legal and regulatory foundations of traditional banking.
Each developed around a different institutional constituency, technological architecture, and understanding of monetary control.
Yet a more consequential possibility is beginning to emerge. Rather than converging around a single digital instrument, the financial system may be preparing to accommodate several forms of money simultaneously, with a new layer of infrastructure responsible for moving value between them.
That distinction changes the nature of the competition.
A stablecoin issuer controls a digital liability and its reserve arrangements. A commercial bank controls deposit relationships and access to regulated banking infrastructure. A blockchain network provides execution and settlement capabilities. But an institution capable of coordinating transactions across these environments could occupy a position that extends beyond any individual monetary instrument.
The emerging question is no longer simply who will issue the digital dollar.
It is who will determine how that dollar moves.
A Consortium Is Forming Around the Digital Dollar
The decision by 21 financial institutions to pursue a jointly issued dollar stablecoin offers one indication of how traditional finance is responding to this transition.
The initiative, announced in September 2026, brings together major institutions including Goldman Sachs, Bank of America, Citi, and Deutsche Bank. The group intends to establish a separate issuing company during the second half of 2026, with an initial dollar-denominated stablecoin targeted for the first half of 2027. Expansion into other major currencies, beginning with the euro, is also contemplated.
The consortium’s significance extends beyond the prospect of another regulated stablecoin entering an increasingly competitive market.
Banks have historically maintained distinct deposit liabilities, payment relationships, compliance obligations, and settlement arrangements. A shared stablecoin could create a common instrument capable of circulating among institutions and customers that would otherwise depend on separate banking infrastructures.
Such an arrangement could reduce some of the operational fragmentation associated with cross-border payments and digital-asset settlement.
But the announcement leaves several consequential questions unanswered.
The consortium has not publicly established the complete ownership and governance structure of its proposed issuer. The detailed reserve composition, redemption arrangements, selected blockchain networks, and necessary regulatory authorizations remain unresolved in the available disclosures.
Those omissions are not incidental. They will determine whether the proposed instrument functions primarily as a payment token, an institutional settlement asset, or a broader bridge between conventional banking and blockchain-based markets.
They also establish an important analytical boundary: the consortium has announced an intention to issue digital money, not a fully developed routing architecture.
The evidence for that larger architecture is emerging elsewhere.
Citi Is Connecting the Two Sides of the Transaction
On September 28, Citi and Coinbase announced an expanded collaboration intended to connect conventional banking services with stablecoin payments.
The arrangement approaches the problem from two directions.
Through Coinbase Virtual Accounts, Citi’s regulated Virtual Account Wallet infrastructure will provide bank-account-like functionality while enabling incoming fiat payments to be converted automatically into stablecoins.
In the opposite direction, Citi’s Spring payment platform will allow institutional merchants to accept stablecoin payments using Coinbase Payments, with conversion into fiat and settlement handled by Citi as the bank of record.
The significance lies in what the customer may no longer need to manage.
A business receiving a conventional bank payment could obtain stablecoin functionality without constructing its own banking integration. A merchant accepting stablecoins could receive fiat without independently managing blockchain custody, conversion, and settlement.
The transaction crosses two monetary environments, yet the underlying complexity is absorbed by the institutions coordinating it.
This introduces a different competitive proposition.
The customer is purchasing the ability to move value, not necessarily exposure to the monetary instrument used during the transaction.
That distinction could become increasingly important as financial institutions seek to incorporate blockchain settlement without requiring corporate clients to restructure their treasury operations around digital assets.
Citi’s initiative does not establish that all monetary instruments are interchangeable, nor does it demonstrate unrestricted routing across every blockchain. The announced capabilities are specific integrations, initially focused on the United States.
Nevertheless, they illustrate how banking and digital-asset infrastructure can be combined into a service in which conversion and settlement mechanisms operate behind the customer-facing interface.
The strategic asset may be the relationship that determines which infrastructure is used.
Swift Is Developing the Coordination Layer
While Citi and Coinbase are connecting bank accounts with stablecoin payment infrastructure, Swift is approaching the problem through interbank coordination.
In July 2026, Swift announced that its blockchain-based shared ledger was ready for initial use, with 17 banks preparing to pilot cross-border transactions involving tokenized deposits.
Unlike conventional stablecoins, tokenized deposits represent commercial bank liabilities maintained within the regulated banking system. Their economic and legal characteristics depend on the issuing bank and the applicable deposit arrangements.
Swift’s model allows participating institutions to coordinate transfers involving tokenized deposits held on their respective ledgers, while final settlement continues through established mechanisms.
This architecture is particularly revealing.
The banks are not necessarily being asked to abandon their existing monetary liabilities or transfer complete control of settlement to a common blockchain. Instead, Swift provides a shared environment for validating commitments, coordinating transactions, and maintaining visibility across participating institutions.
Its initial technical design uses an Ethereum Virtual Machine-compatible architecture based on Hyperledger Besu. Banks retain authority over their own assets, signing keys, funding arrangements, and settlement processes.
The shared ledger therefore becomes a coordination mechanism rather than a replacement for the entire banking system.
That model could preserve important characteristics of commercial bank money while extending transaction availability beyond the operating hours of traditional payment systems.
It also suggests that interoperability may develop through coordinated obligations and settlement instructions, rather than requiring every institution to issue the same token on the same blockchain.
In such a system, the network that coordinates the transaction can become strategically significant even when it does not itself issue the money.
The Chainlink Development Adds Another Dimension
The September 28 announcement involving Chainlink and Swift introduces another component: programmable orchestration between bank-controlled systems and shared transaction infrastructure.
Chainlink is developing connectivity that would allow financial institutions to access Swift’s ledger through the Chainlink Runtime Environment while retaining control of the private keys authorizing transactions.
This separation matters.
Banks can preserve their internal approval processes and security controls while an external orchestration environment coordinates workflows involving their ledgers and Swift’s shared infrastructure.
A separate demonstration for Swift’s 2026 Hackathon extended the concept into tokenized securities.
Chainlink demonstrated a workflow for processing dividend payments across four blockchain networks, using existing financial messaging standards, automated compliance checks, and cross-chain infrastructure.
Recipients could receive payment in a stablecoin or tokenized deposit on their designated network, with the system coordinating entitlements, execution, and reconciliation.
This was a demonstration, not evidence of a fully deployed institutional dividend-processing service.
But its architectural implications are considerable.
A financial institution managing tokenized securities may eventually need to determine which blockchain contains an asset, which investor is entitled to payment, which settlement instrument is acceptable, and which regulatory requirements govern the transaction.
Those decisions must be coordinated before a transfer can be completed reliably.
The underlying blockchain performs an important function, but it does not independently resolve every obligation associated with the transaction.
A programmable orchestration layer can bring those requirements into a common workflow.
That capability could become especially valuable as tokenized financial instruments proliferate across public and permissioned networks.
The First Live Transactions Change the Evidence
The transition from architectural planning to practical execution is already underway.
On August 19, Standard Chartered and HSBC announced their first live cross-border transaction using tokenized deposit interoperability through Swift’s blockchain-based ledger.
Citi subsequently reported live transactions with First Abu Dhabi Bank and OCBC, extending the experiment into the Middle East and Southeast Asia. These transactions belong to a controlled proof-of-concept program scheduled to run through December 2026.
The distinction between demonstration and commercial scale remains important. A successful controlled transaction does not establish sustained throughput, broad institutional adoption, or superior economics across every payment corridor.
Nevertheless, the evidence has advanced beyond theoretical interoperability.
Separate banks have begun demonstrating how their respective deposit infrastructures can interact through a shared coordination environment without requiring every institution to surrender its existing monetary architecture.
For the broader stablecoin market, this creates an interesting competitive tension.
A bank-issued stablecoin could provide a common transferable asset. A tokenized-deposit network could preserve institution-specific liabilities while coordinating their movement. A payment orchestration service could potentially connect both with conventional bank balances.
These are not necessarily mutually exclusive strategies.
The institution controlling access between them may eventually be able to support all three.
The Reserve Model Still Determines the Monetary Risk
The emergence of orchestration infrastructure does not eliminate the fundamental distinctions between different forms of money.
A stablecoin backed by Treasury securities and cash equivalents carries a different legal and financial structure from a tokenized commercial bank deposit. The former depends on the issuer’s reserve assets, redemption obligations, custody arrangements, and applicable legal protections. The latter remains connected to the balance sheet and creditworthiness of the issuing bank.
Neither structure becomes risk-free simply because its transfer mechanism operates on a blockchain.
The consortium’s earlier feasibility work contemplated a one-to-one reserve-backed digital instrument available on public blockchains. Its September announcement, however, did not establish the final reserve portfolio, issuance structure, or blockchain selection.
Regulatory requirements will influence those decisions.
In September, the Federal Reserve proposed implementing rules for payment stablecoin issuers under its supervision, including permissible reserve assets, capital requirements, operational safeguards, and custody standards. These remain proposals rather than approvals of the consortium’s intended structure.
The distinction is particularly relevant when considering how a future routing layer might operate.
A transaction moving between a bank deposit and a stablecoin may require more than a change of technical network. It can involve redemption of one liability, issuance or acquisition of another, foreign-exchange conversion, liquidity provision, and separate settlement obligations.
The routing infrastructure must therefore account for the legal character of the money, not merely its digital representation.
This is where financial orchestration becomes more demanding than conventional blockchain interoperability.
Moving a token between compatible networks is one problem. Coordinating a transfer between different issuers, liability structures, jurisdictions, and settlement systems is another.
The second problem may prove substantially more valuable to solve.
Control May Migrate Toward the Routing Decision
If multiple forms of digital money coexist, financial institutions and their customers will increasingly face choices about which instrument and network to use.
A corporate treasury operation may prefer a tokenized bank deposit for internal liquidity management, a regulated stablecoin for a digital-asset transaction, and conventional bank settlement for a supplier operating outside blockchain infrastructure.
The customer may not want to manage these distinctions manually.
A sufficiently developed orchestration platform could evaluate available liquidity, transaction costs, settlement certainty, regulatory eligibility, network availability, and counterparty preferences before selecting an appropriate path.
That capability introduces a potentially powerful economic position.
The operator controlling transaction routing could influence which issuers receive volume, which networks capture activity, which liquidity providers participate, and where conversion services generate revenue.
Over time, routing decisions could also influence the distribution of liquidity across competing monetary instruments.
This does not mean an orchestration provider automatically acquires authority over the underlying money. Banks, issuers, customers, and regulators retain important legal and operational controls. Nor does it establish that one company will dominate the emerging infrastructure.
Competition could develop among bank-operated networks, payment processors, blockchain interoperability providers, and specialized financial software companies.
But the strategic focus would begin to shift.
Issuance creates the instrument. Distribution creates access. Orchestration determines how the instrument participates in the wider financial system.
The value of that final function could increase as the number of networks and monetary instruments expands.
The Banks May Not Need One Winning Blockchain
The financial industry’s blockchain debate has often assumed that network adoption will determine which infrastructure ultimately dominates institutional digital finance.
That assumption becomes less convincing if financial institutions can coordinate activity across multiple networks while maintaining distinct settlement arrangements.
Public blockchains may continue to provide important infrastructure for transferable stablecoins and tokenized assets. Permissioned networks may remain attractive for regulated banking workflows. Existing payment systems may continue to perform final settlement where their legal and operational characteristics are preferable.
A routing architecture could allow these environments to coexist.
The result would not be a single universal ledger, but an increasingly connected collection of monetary systems.
That prospect carries implications for blockchain economics.
Network transaction volume may remain important, but it would not necessarily correspond directly with control over the customer relationship or the financial transaction.
An intermediary capable of directing transactions across networks could capture strategic value without operating the underlying blockchain or issuing the settlement asset.
Conversely, blockchain networks that offer reliable interoperability, sufficient liquidity, predictable settlement, and institutional-grade integration could become more attractive destinations within that architecture.
The competitive advantage may increasingly depend on how effectively a network participates in the broader financial system, rather than whether it can persuade the entire system to migrate onto its own ledger.
A New Financial Control Layer Is Taking Shape
The 21-institution stablecoin consortium remains an important development, but its eventual significance may depend on more than the adoption of its proposed token.
Its reserve arrangements, regulatory authorizations, governance structure, and blockchain choices will determine the characteristics of the instrument itself.
The surrounding infrastructure will determine how widely that instrument can move.
Citi and Coinbase are developing services that connect conventional payments with stablecoin settlement. Swift is coordinating tokenized deposits across participating banks. Chainlink is demonstrating how programmable workflows can connect distinct blockchain environments with established financial messaging and institutional controls.
These initiatives remain at different stages of maturity and should not be mistaken for a single coordinated platform.
Taken together, however, they point toward a financial architecture in which monetary instruments and transaction infrastructure become increasingly separable.
That separation could alter the economics of digital finance.
The issuer may earn returns associated with reserve management or banking relationships. The blockchain may earn fees for execution and settlement. The liquidity provider may earn compensation for conversion and market-making.
The routing provider could occupy the position connecting those activities.
Whether that position becomes a major source of durable financial power will depend on adoption, governance, interoperability, competitive access, and the economics of actual transactions.
For now, the institutional direction is becoming clearer.
The next stage of digital money may not require banks to choose between stablecoins, tokenized deposits, and conventional balances. It may require them to build systems capable of making those instruments work together.
The banks are preparing to issue new forms of money.
The more consequential development may be the infrastructure deciding where that money goes.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.