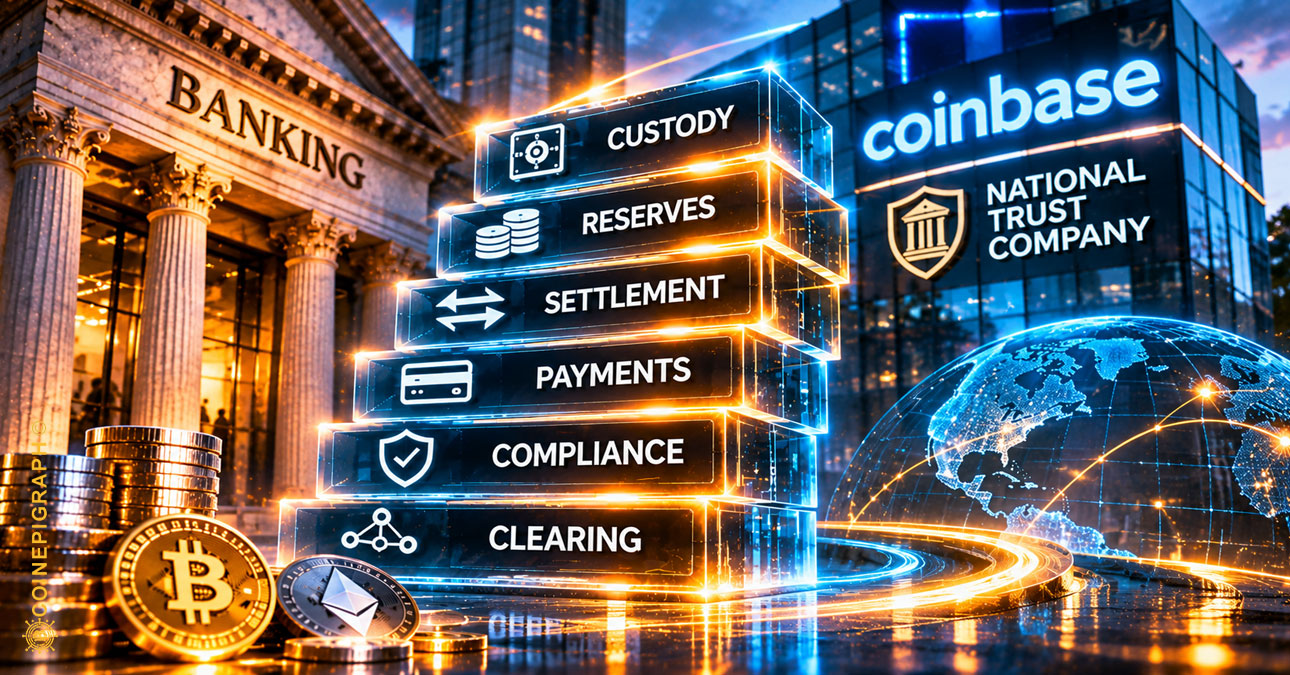
Coinbase did not become a conventional bank when federal regulators approved its national trust company. It obtained something narrower—and potentially more revealing about where digital finance is heading. Custody, reserves, settlement and other functions once bundled inside banks are beginning to emerge as separately regulated pieces of financial infrastructure.
By CoinEpigraph Editorial Desk
Coinbase became a bank this month.
That statement is technically close enough to make a headline and incomplete enough to obscure what actually happened.
On November 6, the Office of the Comptroller of the Currency granted final conditional approval to charter Coinbase National Trust Company. The OCC authorized the institution to open three days later and approved it to provide cryptocurrency custody in a fiduciary capacity.
Coinbase did not receive permission to become the kind of bank most people recognize.
The new institution is a non-insured national trust company. Its purpose is not to gather checking deposits and turn them into mortgages, business loans and credit lines. Coinbase’s trading, staking and other businesses do not simply move inside the charter.
The function at the center of the approval is custody.
That narrower distinction may be considerably more important than the headline.
For most of modern financial history, banks accumulated functions. They accepted deposits, moved money, safeguarded assets, extended credit, administered trusts and connected customers to payment systems. Different institutions specialized, but the banking system became a collection of organizations in which multiple financial functions often lived under one regulated roof.
Digital finance may be pushing in another direction.
Custody can become its own federally supervised institution. Stablecoin reserves can sit inside another regulated structure. Trading can remain somewhere else. Settlement can increasingly operate through specialized infrastructure. Payments can travel across still another network.
The institution is being separated into functions.
And crypto companies are beginning to occupy those functions one at a time.
Custody Came First for a Reason
Coinbase National Trust Company did not emerge from nowhere.
Coinbase has operated a New York-regulated custody business for years. Its institutional custody operation has become particularly important as digital assets have moved into conventional investment products.
That means the OCC charter is not primarily about creating a new Coinbase product.
It changes the regulatory architecture around an existing function.
The OCC’s approval says Coinbase National Trust Company will provide cryptocurrency custody in a fiduciary capacity. That wording carries more weight than simply storing private keys. A fiduciary operates under duties governing how assets belonging to others are administered.
For an industry built around the proposition that holders could control assets themselves, the institutional market has been moving in an almost opposite direction.
Large pools of capital generally do not want an employee keeping billions of dollars of Bitcoin on a hardware wallet.
They want segregation of assets. Controls. Audits. Governance. Legal accountability. Operational resilience. A regulated entity that can be held responsible for performing the custody function.
The asset may be native to a blockchain.
The institutional relationship surrounding it is becoming increasingly recognizable to traditional finance.
That is why custody is a logical place for the boundary between the two systems to move.
The Bank Is Being Unbundled
Coinbase is easier to understand when viewed alongside other digital-asset firms seeking national trust structures.
The individual businesses are not identical, and neither are the powers associated with their charters. That distinction should not be flattened.
What matters is the direction.
Digital-asset companies are increasingly seeking regulated institutional structures for particular financial functions rather than attempting to reproduce every activity of a commercial bank.
That creates a different model of financial integration.
A stablecoin company may need regulated infrastructure for reserves.
An asset manager needs qualified custody.
A tokenized security needs issuance, recordkeeping, trading, custody and settlement.
An institutional investor needs assets held under a legal and supervisory framework its own compliance department recognizes.
Those activities historically intersected with banks, broker-dealers, clearing organizations, transfer agents and custodians.
Blockchain does not make those functions disappear.
It can change where they reside.
This is becoming one of the more consequential transitions in digital finance. Crypto spent much of its early history constructing an alternative financial architecture outside conventional institutions. The institutional phase increasingly looks less like replacement and more like selective integration.
But integration does not necessarily mean putting everything back inside the old bank.
It may mean pulling the bank apart.
A Trust Charter Is Not a Commercial Bank Charter
This is where the distinction around Coinbase matters.
A national trust company sits inside the federal banking framework, but that does not make it economically equivalent to JPMorgan Chase or a community bank.
Coinbase National Trust Company is non-insured. Its approved business centers on fiduciary custody. The charter itself does not transform Coinbase’s broader exchange operation into a federally chartered commercial bank.
That limitation is not incidental.
It shows how regulatory status can increasingly attach to a function rather than to the entire financial enterprise surrounding it.
Coinbase can operate an exchange through one corporate structure while custody of institutional assets moves into another.
The separation creates boundaries.
Those boundaries determine which regulator supervises an activity, what capital and governance requirements apply, where customer assets sit and which risks remain outside the regulated entity.
That is more useful than asking whether Coinbase is now a bank.
The better question is what part of banking Coinbase has been authorized to perform.
For now, the answer is concentrated around fiduciary custody.
Tomorrow’s answer across digital finance may be more complicated.
The Custodian Is Becoming Infrastructure
Custody can sound passive.
It isn’t.
As tokenized finance develops, custody increasingly sits near the intersection of ownership, settlement and regulatory recognition.
Consider the institutional chain surrounding a conventional spot crypto investment product.
An investor may own shares in a regulated fund rather than cryptocurrency directly. The fund owns the underlying digital asset. Someone must safeguard that asset. Someone must maintain controls around movement. Someone must establish who has authority to initiate transactions. Someone must reconcile records when assets move.
The blockchain can establish that an asset moved between addresses.
It does not, by itself, establish whether the employee who authorized the transfer had legal authority to do so.
That remains an institutional problem.
Custody is where part of that problem gets resolved.
The same issue becomes more important as tokenization expands beyond cryptocurrency.
If securities, funds, private assets and other financial claims increasingly acquire blockchain representations, institutions will still need legally accountable organizations that determine how those assets are held and who is permitted to act on them.
The ledger may become programmable.
Fiduciary responsibility does not disappear with it.
That gives regulated digital custody a role much larger than simply protecting cryptocurrency from theft.
It can become part of the ownership architecture of tokenized capital markets.
Why Traditional Banks Are Paying Attention
The resistance from banking organizations is therefore understandable even without reducing the dispute to incumbents protecting their territory.
The underlying question is regulatory perimeter.
If a company can obtain a national trust charter, perform a significant financial function and operate under federal banking supervision without assuming the full obligations or business model of a deposit-taking commercial bank, what exactly constitutes entry into banking?
That question becomes more difficult as technology separates activities that banks historically bundled together.
Traditional banking regulation developed around institutions.
Digital financial architecture increasingly allows institutions to be decomposed.
Custody can sit here.
Trading there.
Stablecoin issuance somewhere else.
Reserve administration somewhere else again.
Settlement can operate through a blockchain while access to that blockchain remains controlled by regulated entities.
The resulting system may contain many familiar banking functions without organizing all of them around the familiar bank.
That is not deregulation by definition.
Some of these entities may be intensively supervised.
It is a different allocation of regulated responsibility.
Stablecoins Show Where This Can Lead
Stablecoins make the functional model easier to see.
A dollar-backed stablecoin involves several activities that appear unified to the user.
A token is issued.
Reserves are held.
Those reserves are administered.
Tokens are redeemed.
Payments or transfers occur across a network.
Compliance controls determine who can interact with certain parts of the system.
Yet none of those functions inherently has to reside inside the same legal entity.
The issuer does not necessarily have to be the reserve custodian.
The reserve custodian does not have to operate the payment network.
The network does not have to hold the reserves.
The wallet provider does not have to issue the asset.
What looks like one financial product at the user interface can therefore be a stack of separately governed institutions underneath it.
That architecture is beginning to appear elsewhere.
Tokenized securities can separate issuance from custody and settlement. Digital wallets can separate asset control from the underlying network. AI agents may eventually initiate financial instructions without becoming custodians of the assets they are authorized to move.
The pattern is the same.
Financial functions that once appeared inseparable can become modular.
Regulation then has to follow the module.
Federal Supervision Changes the Institutional Conversation
Coinbase’s move from a state trust framework toward a federally chartered custody institution matters partly because institutional finance values regulatory legibility.
That does not mean federal supervision makes cryptocurrency safe.
Nor does a national charter remove market, technology, operational or counterparty risk.
It changes who supervises the institution performing a particular function and creates a more nationally uniform framework around that activity.
That can matter to asset managers, retirement administrators, corporations and other institutions whose participation depends as much on legal architecture as technological capability.
The crypto industry spent years asking whether institutions would become comfortable holding digital assets.
The more interesting development may be that the infrastructure around those assets is being rebuilt into forms institutions already know how to evaluate.
The cryptocurrency does not have to become conventional.
The institution holding it can.
The Boundary Is Moving
Coinbase’s regulatory history makes the transition particularly visible.
Only a few years ago, the company’s relationship with Washington was dominated by disputes over whether significant parts of its business fit within existing securities regulation.
Now another federal regulator has chartered a Coinbase subsidiary to perform fiduciary cryptocurrency custody.
Those two facts should not be collapsed into a story about Washington reversing itself. Different agencies regulate different activities under different statutes.
The more useful observation is institutional.
Digital assets have moved far enough into mainstream financial markets that regulators are increasingly confronting not merely whether crypto should be permitted, but where specific crypto-related functions belong inside the existing supervisory architecture.
That is a different stage of development.
The debate moves from whether crypto sits outside finance to which parts of financial regulation should govern which pieces of crypto infrastructure.
Custody is one answer.
It will not be the last.
Banking Without the Whole Bank
There is an irony in the direction digital finance is taking.
Crypto began with an architecture designed partly to eliminate financial intermediaries.
Institutional adoption is producing a growing collection of specialized intermediaries around the technology.
But they are not necessarily recreating the bank as it existed before.
They may be recreating its functions separately.
A federally regulated custodian can hold the asset.
Another institution can manage reserves.
An exchange can provide liquidity.
A blockchain can provide settlement infrastructure.
A wallet can provide the interface.
A payment company can provide distribution.
A regulated issuer can create the financial claim.
Each layer can have different economics, different risks and potentially a different regulator.
That raises the question CE has repeatedly encountered as financial infrastructure becomes more programmable:
Who controls the function that matters?
Coinbase National Trust Company provides one answer for custody.
The larger transformation will become visible when enough of those answers are placed beside one another.
At that point, the story may no longer be that crypto companies entered banking.
It may be that banking itself was reorganized into pieces—and digital-finance companies began taking their places among them.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.