The African Union has backed a new credit rating institution headquartered in Mauritius. Its promise of financial sovereignty now faces a more consequential test involving ownership, governance, independence, and the economics of African borrowing.
By CoinEpigraph Editorial Desk
The price of capital is never determined by interest rates alone. Before a government issues a bond, before an institutional investor commits capital, and before a lender establishes its terms, someone must decide how much risk the borrower represents.
For much of Africa, that judgment has been shaped by credit rating institutions headquartered outside the continent.
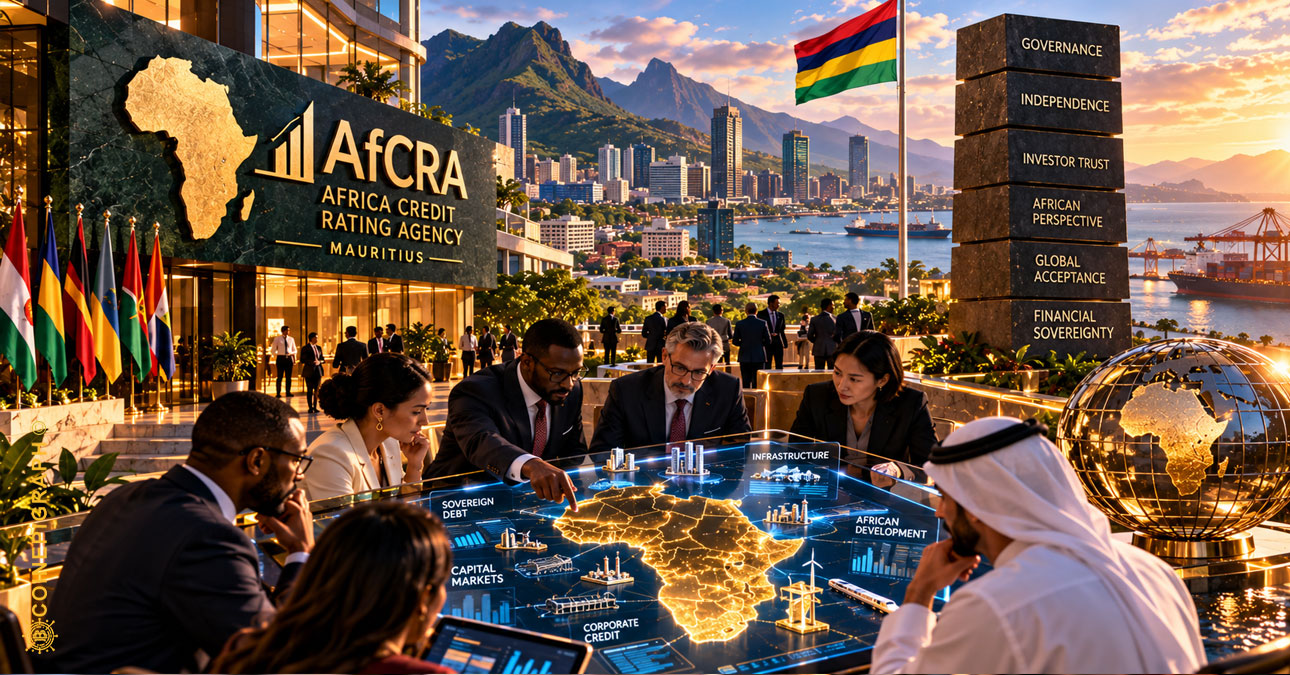
On October 7, 2026, the African Union took a significant step toward changing that arrangement with the official launch of the Africa Credit Rating Agency (AfCRA) in Mauritius.
The institution arrives with an ambitious mandate: introduce deeper African economic knowledge into credit assessments, improve the information available to investors, and strengthen the continent’s participation in determining how its financial risks are evaluated.
Yet the significance of AfCRA extends beyond the establishment of another rating agency.
It raises a more fundamental question about financial sovereignty.
Who ultimately controls the institutions that determine how African risk is understood, priced, and distributed throughout global capital markets?
The answer will depend less on the agency’s geographic identity than on its ownership, governance, analytical independence, and acceptance by investors.
The Price of Being Understood
Credit ratings occupy a powerful position within international finance.
They influence investment mandates, borrowing eligibility, collateral treatment, and the willingness of institutions to hold particular securities.
A sovereign borrower assigned a lower rating may encounter a smaller investor universe, higher financing costs, or more restrictive borrowing conditions.
These consequences become especially significant for developing economies attempting to finance infrastructure, industrial expansion, healthcare, and energy systems.
African policymakers have long argued that international rating methodologies sometimes fail to capture important features of their economies.
The criticism is not simply that ratings are unfavorable. It concerns whether the information and assumptions underlying those ratings adequately reflect local conditions.
The United Nations Economic Commission for Africa has cited estimates suggesting that persistent risk premiums impose approximately $75 billion in annual excess financing costs on the continent.
That estimate illustrates the potential scale of the problem, although it should not be interpreted as a proven amount that AfCRA could recover.
Nor is the underlying debate settled. The major international agencies maintain that they apply consistent methodologies, and independent investigations have questioned claims of systematic bias.
The distinction matters.
An African rating agency cannot establish credibility merely by producing more favorable assessments.
It must demonstrate that its conclusions contain information investors were previously missing.
Mauritius: An African Financial Gateway
The decision to establish AfCRA in Mauritius introduces another dimension to the project.
Mauritius is geographically and institutionally African. It belongs to the African Union and participates in major continental economic organizations.
Its population, however, reflects a distinctive historical and cultural composition shaped by African, Indian, European, and Chinese influences.
Individual identification with those traditions varies.
That cultural complexity does not diminish Mauritius’s standing as an African state.
For AfCRA, the more consequential consideration is the country’s position within international finance.
Mauritius has developed an established financial-services sector serving investors, corporations, and investment structures operating across African and international markets.
Its legal and regulatory environment, professional-services capacity, and cross-border financial relationships help explain its attraction as a headquarters location.
The African Peer Review Mechanism confirmed that Mauritius was selected through a competitive process administered with transaction-adviser support.
In February 2025, the APRM appointed advisers from Mauritius Commercial Bank to assist with the agency’s establishment.
This involvement is documented and does not, by itself, establish any conflict of interest.
Nevertheless, the relationship between AfCRA’s institutional development and the financial sector of its host jurisdiction deserves scrutiny.
Mauritius is not merely providing office space.
It is offering an established international financial environment through which a new African credit-information institution can develop.
That creates an important distinction between locating an institution in Africa and determining how its economic influence will be exercised.
The Ownership Question
AfCRA has been structured as a private-sector-driven institution intended to operate independently of government ownership.
The reasoning is understandable.
An agency evaluating sovereign borrowers cannot credibly function as an instrument through which those same governments dictate their own creditworthiness.
Political independence is therefore essential.
But independence from governments does not automatically establish independence from commercial interests.
Credit rating agencies also face potential conflicts involving shareholders, paying clients, financing arrangements, and institutional relationships.
For AfCRA, several questions remain important.
Who ultimately owns the institution?
How is its shareholder capital distributed?
Who appoints its directors?
What authority does management possess over rating methodologies?
How are conflicts between shareholders, clients, and analytical personnel resolved?
Public reporting surrounding the launch did not provide a complete picture of the agency’s shareholder structure.
The United Nations has identified Sifiso Falala as its chief executive, while reporting indicates that AfCRA received a Mauritius financial-services licence before its formal launch.
Those developments establish meaningful progress toward operational readiness.
They do not resolve the larger ownership and governance questions.
There is no basis in the information reviewed to conclude that AfCRA’s ownership arrangements are improper.
There is, however, a strong public-interest argument for transparent disclosure.
An institution established to improve financial transparency across Africa should be prepared to demonstrate transparency within its own governance.
Independence Will Be Tested by Uncomfortable Ratings
AfCRA’s greatest challenge may emerge when its conclusions disappoint the very institutions that supported its creation.
Consider a sovereign government that expects an African rating agency to recognize economic improvements overlooked by international competitors.
If AfCRA reaches the same unfavorable conclusion as those competitors—or assigns an even weaker rating—will that assessment be accepted?
Will the agency retain its independence when influential borrowers object?
These are not hypothetical concerns unique to Africa.
Credit rating institutions everywhere must manage the tension between commercial relationships and independent analysis.
The credibility of a rating ultimately depends on whether investors believe the underlying judgment can withstand political and financial pressure.
AfCRA will therefore need more than regional expertise.
It will require transparent methodologies, defensible assumptions, strong analytical personnel, reliable data, and a record of decisions that remain consistent under difficult conditions.
The objective cannot be to replace unfavorable foreign opinions with favorable domestic ones.
It must be to improve the quality of financial information available to the market.
The Missing Layer in African Capital Markets
One of AfCRA’s potentially important contributions concerns borrowers that receive limited attention from major international rating agencies.
The African Union has identified 23 African economies without ratings from the three dominant global agencies.
The absence of widely recognized credit assessments can restrict participation by investors whose mandates require rated securities.
Similar information gaps affect municipalities, infrastructure projects, financial institutions, and corporations.
An agency capable of evaluating these borrowers could help expand the universe of African financial instruments available to institutional investors.
This opportunity may be particularly important for local-currency debt markets.
African economies cannot build durable financial independence solely through repeated access to foreign-currency borrowing.
Deeper domestic bond markets, pension-fund participation, regional investment institutions, and credible local credit information can reduce dependence on external financing channels.
AfCRA could contribute to that development.
But producing a rating is only the first step.
Investors must trust it. Regulators must recognize it. Financial institutions must be permitted to incorporate it into their investment and risk-management processes.
Without that acceptance, additional ratings may improve information without materially changing capital allocation.
The Digital Finance Connection
There is another reason this development belongs within a broader examination of financial market structure.
As tokenized securities, digital bonds, and blockchain-based settlement systems develop, reliable credit information becomes increasingly important.
A tokenized government bond still carries sovereign credit risk.
A digitally represented corporate obligation still depends on the issuer’s capacity to repay.
Programmable settlement may improve the movement and administration of financial instruments, but it does not eliminate the economic risks embedded within them.
Credit assessments could eventually become inputs into digital investment platforms, automated portfolio mandates, and institutional risk-management systems.
For African markets, this creates a potential connection between locally generated financial intelligence and emerging digital capital-market infrastructure.
There is currently no verified basis to present AfCRA as operating a blockchain initiative.
The relevance is structural rather than operational.
If Africa develops stronger institutions for assessing credit risk, those institutions could become valuable components of future financial markets regardless of the technology used to issue or settle securities.
Financial Sovereignty Must Produce Economic Results
The establishment of AfCRA represents a meaningful attempt to expand African participation in global financial decision-making.
It also illustrates the complexity of achieving financial sovereignty within an interconnected international system.
Mauritius offers a credible financial-services environment and established connections to international capital.
Those advantages may help the agency develop.
Yet the ultimate measure of success will not be the location of its headquarters or the symbolism of its launch.
It will be whether AfCRA produces assessments that investors trust, whether its governance remains independent, and whether African borrowers gain access to better-informed capital markets.
Financial sovereignty does not require insulation from international scrutiny.
It requires the institutional capacity to participate in that scrutiny on credible and economically meaningful terms.
AfCRA now has the opportunity to demonstrate that such capacity can be developed within Africa.
Its ownership disclosures, rating methodologies, regulatory recognition, and first consequential assessments will reveal how much institutional authority accompanies that ambition.
For a continent seeking greater influence over its financial future, the distinction is decisive.
Establishing an African credit rating agency creates a new institution. Establishing an independent, trusted source of African credit intelligence could begin changing who influences the price of African capital.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.