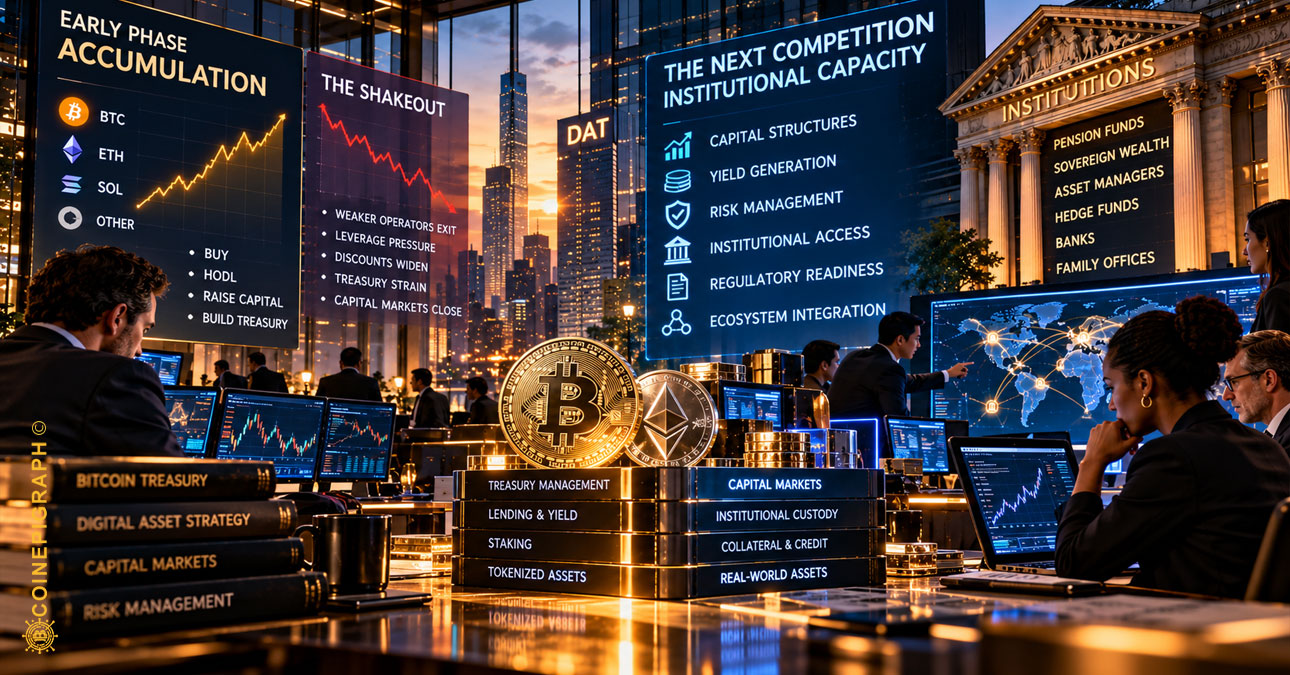
Digital asset treasury companies were initially measured by how much Bitcoin or Ethereum they could accumulate. As weaker operators retreat and stronger ones build increasingly complex capital structures, a different competition is emerging: who can turn digital assets into durable institutional capacity?
By CoinEpigraph Editorial Desk
The digital asset treasury trade is beginning to lose some of its participants.
Sequans Communications sold the remainder of its Bitcoin holdings in September and declared its Bitcoin treasury strategy concluded. KULR Technology Group also liquidated its remaining Bitcoin position after selling roughly 764 BTC between August and September.
Neither example proves that the digital asset treasury model is failing. Companies sell assets for different reasons, and abandoning a treasury strategy is not equivalent to the collapse of an industry.
But the exits matter because they are occurring while other companies are moving in precisely the opposite direction.
Strategy continues to operate one of the world’s largest corporate Bitcoin treasuries while surrounding it with common equity, preferred securities, cash reserves and increasingly elaborate capital-management programs. BitMine Immersion Technologies has accumulated millions of Ether while developing staking and validator infrastructure. Strive has expanded its Bitcoin position through acquisitions and new preferred capital.
The first generation of the digital asset treasury industry was largely measured by accumulation.
The next may be measured by what companies can build around what they accumulated.
That distinction could determine whether DATs remain vehicles for obtaining concentrated exposure to digital assets or begin developing into something more durable: specialized financial institutions whose digital reserves support financing, infrastructure, acquisitions and other forms of capital deployment.
The important question is no longer simply who owns the most Bitcoin or Ethereum.
It is what that ownership eventually makes possible.
Why Another Digital Asset Treasury?
The proliferation of treasury companies has produced an understandable question.
If Michael Saylor’s Strategy already dominates corporate Bitcoin accumulation, why would another company enter the same business?
The question assumes that digital asset treasuries are essentially interchangeable.
They may not be.
Banks compete with banks. Asset managers compete with asset managers. Insurance companies compete with insurance companies. Their existence is not rendered redundant because another institution already performs broadly similar functions.
Digital asset treasury companies could eventually develop the same kind of differentiation.
For now, however, much of the industry still depends upon a relatively simple proposition. A company acquires Bitcoin, Ether or another digital asset. Investors assign the company’s shares some value based partly upon that exposure. When the stock trades sufficiently above the value of the underlying assets, the company can raise additional capital under favorable conditions and acquire more.
That mechanism becomes much less forgiving when the premium disappears.
Research published by DWF Labs in September found that only four of the 20 largest digital asset treasury companies in its sample were trading above 1x market net asset value. BitcoinTreasuries subsequently found widespread compression below net asset value during the 2026 market stress.
Once a company’s equity no longer commands a premium to its treasury, issuing additional shares can become increasingly dilutive. Financing costs matter more. Operating cash flow matters more. Liquidity matters more.
And management begins mattering considerably more.
The distinction emerging across the industry may therefore be less about size than about capital architecture.
Saylor, Lee and the Long Game
Strategy provides the clearest example.
By late July, the company reported holding 843,775 BTC. It had raised more than $17 billion through at-the-market programs during 2026 and another $7.5 billion through STRC, one of the preferred securities that now surround its Bitcoin treasury.
The structure is no longer adequately described as a corporation buying Bitcoin.
Strategy has developed multiple securities offering different combinations of yield, volatility and exposure to the company’s underlying financial position. It maintains a dollar reserve intended to support preferred dividends and debt interest. It has established repurchase programs for its preferred securities and formalized circumstances under which Bitcoin can be monetized to meet capital-management requirements.
The treasury is becoming surrounded by its own financial machinery.
That does not eliminate its dependence upon Bitcoin.
It makes that dependence more sophisticated.
If Bitcoin appreciates substantially over time, Strategy’s balance sheet could become considerably more powerful. But appreciation does not automatically translate into unrestricted borrowing capacity. Lenders impose collateral requirements. Markets impose financing costs. Preferred securities create obligations. Equity issuance can dilute existing shareholders. Volatility can reduce the amount of credit available against an asset precisely when liquidity is most valuable.
The treasury can create financial capacity while simultaneously creating new financial obligations around itself.
BitMine offers a different experiment because Ethereum is a different asset.
As of October 25, BitMine reported approximately 6.05 million ETH, with roughly 5.23 million ETH staked. The company estimated that its staking operation was producing approximately $318 million in annualized revenue at prevailing rates.
More important than the yield itself is what BitMine has begun building around it.
Its MAVAN validator infrastructure, originally developed to service the company’s own Ethereum holdings, has expanded toward institutional customers including custodians and other market participants.
That begins to cross an important boundary.
The treasury is no longer simply appreciating or generating yield. Infrastructure developed to manage the treasury is becoming a service that can potentially generate revenue from outside customers.
Bitcoin and Ethereum treasury models therefore should not be treated as identical versions of the same trade.
Bitcoin offers monetary scarcity, liquidity and an increasingly institutionalized capital market. Ethereum combines an investable reserve asset with native staking and programmable infrastructure.
Neither guarantees a successful treasury institution.
They simply provide different raw materials from which one might be constructed.
Strive Tests Whether There Is Room for Another Model
Strive helps answer why another company might enter an industry already dominated by Strategy.
The company completed its acquisition of Semler Scientific in January, inheriting a substantial Bitcoin position in the process. By October 23, Strive reported approximately 43,000 BTC after acquiring another 6,182 BTC during the preceding week.
But its balance sheet also reveals a broader capital strategy.
Strive held more than $500 million in cash and approximately $50 million of Strategy’s STRC preferred securities. This month it raised roughly $630 million through an offering of perpetual preferred stock, with proceeds available not only for Bitcoin purchases but also for income-generating assets, working capital and capital management.
This does not establish that Strive has discovered a superior model.
It establishes that the competition is beginning to involve more than accumulating the same asset.
Acquisitions, preferred capital, liquidity management and income-producing investments introduce decisions about how capital should be allocated around the treasury.
That is where digital asset treasury companies begin looking less alike.
When the Treasury Becomes a Financial Institution
The most consequential possibility is also the easiest to exaggerate.
A company holding $10 billion of Bitcoin does not become a bank because Bitcoin appreciates to $30 billion.
A larger treasury does, however, potentially change what the institution can do.
A stronger balance sheet can improve access to financing. Assets can support structured securities. Capital can finance acquisitions. Liquidity can be deployed into investments capable of producing cash flow.
The institutional transformation occurs only when accumulated wealth becomes usable financial capacity.
That provides a useful test for the DAT industry.
A treasury has one kind of utility when it appreciates on the balance sheet.
It has another when it supports financing or generates revenue.
And it becomes something more consequential when the institution can deploy the resulting capital into productive assets, infrastructure, services or external businesses.
Not every DAT needs to reach that stage.
Some may remain intentionally simple vehicles offering investors exposure to a particular digital asset. That can itself be a legitimate financial product.
But companies aspiring to become durable institutions will eventually have to demonstrate something beyond accumulation.
They will have to show what the treasury can do.
The Shakeout
The companies leaving the trade provide the other side of the experiment.
Sequans sold its remaining 314 BTC in September and explicitly ended its Bitcoin treasury strategy as it redirected attention toward its semiconductor operations.
KULR sold approximately 764 BTC for $58.6 million between August 20 and September 11, leaving the company with no remaining Bitcoin.
These exits should not be interpreted as proof that every smaller treasury company will disappear. Nor should every asset sale be described as an exit. Companies can reduce positions to service debt, finance operations or rebalance capital without abandoning the strategy altogether.
What the current environment does demonstrate is that holding digital assets is not sufficient to create a durable treasury institution.
When market premiums contract, companies lose one of the easiest mechanisms for financing additional accumulation. If operating cash flow is weak and external capital becomes expensive, the treasury can shift from strategic asset to liquidity constraint.
Size helps, but size alone does not solve that problem.
An institution with fewer assets, lower financing costs and disciplined capital allocation could ultimately prove more resilient than a larger competitor carrying expensive obligations.
That suggests the next phase of competition will be fought on the liabilities side of the balance sheet as much as the assets side.
Geography Will Eventually Matter
Digital assets are global.
Treasury companies are not.
They are incorporated somewhere. Their securities trade somewhere. Their assets are custodied within legal structures. Their financing is raised through particular capital markets. Their shareholders, regulators and tax obligations exist within jurisdictions.
That means two companies holding the same quantity of Bitcoin can operate under very different financial conditions.
The United States offers extraordinarily deep public capital markets and increasingly sophisticated digital-asset custody infrastructure. Japan has developed its own corporate Bitcoin treasury sector while its market institutions wrestle with how such companies should be classified within equity benchmarks.
Singapore and the United Arab Emirates are developing regulatory frameworks intended to accommodate institutional digital-asset activity while maintaining financial-market controls.
The significance is not that DATs are about to become instruments of national power.
There is insufficient evidence for that conclusion.
The more immediate point is that jurisdiction affects what these companies can become.
Regulation determines which securities they can issue. Capital markets influence financing costs. Custody rules affect asset management. Tax treatment changes economics. Index providers determine access to pools of passive capital.
The digital asset may move globally.
The institution built around it remains geographically constrained.
Over time, that could produce different regional models of digital asset treasury companies just as different jurisdictions developed distinctive banking, insurance and asset-management industries.
The Limits of Digital Asset Leverage
The bullish version of the DAT thesis is straightforward.
Accumulate scarce digital assets early. Allow appreciation to strengthen the balance sheet. Use that strength to raise capital. Deploy the capital into additional assets, acquisitions or productive investments. Repeat.
The problem is that financial structures rarely operate only in the favorable direction.
Digital assets remain volatile.
A treasury valued at $20 billion during favorable markets can become considerably smaller without management selling anything. Creditors respond by changing collateral requirements. Equity investors demand different valuations. Preferred shareholders still expect dividends. Debt still matures.
And a company that built its financial structure around permanent asset appreciation may discover that its liabilities are considerably less volatile than its assets.
That is why the retreat of weaker DAT operators matters.
They are testing the proposition under real financial conditions.
The companies that survive will not necessarily be those that made the boldest accumulation forecasts. They may be those that preserved liquidity, controlled dilution, managed financing costs and resisted using temporary market premiums as though they were permanent capital.
The treasury can provide leverage.
It can also magnify mistakes.
Beyond Accumulation
Digital asset treasury companies began with a proposition simple enough to explain in a sentence: corporations could hold Bitcoin and other digital assets on their balance sheets.
The industry emerging around that proposition is becoming considerably harder to describe.
Strategy has built a complex securities architecture around Bitcoin.
BitMine is combining Ethereum accumulation with staking and institutional validator infrastructure.
Strive is combining Bitcoin accumulation with acquisitions, preferred capital and broader capital allocation.
Other companies are leaving the trade altogether.
That does not yet constitute a new financial industry.
But it does suggest that the first competitive phase—who can accumulate the most digital assets—is giving way to a more difficult one.
Companies now have to demonstrate whether those assets can support an institution when markets are unfavorable as well as when they are rising.
The distinction matters because accumulation and capital formation are not the same thing.
Owning a valuable asset can make a company wealthy.
Turning that wealth into financing capacity, recurring revenue, useful infrastructure and disciplined capital deployment requires an entirely different set of capabilities.
That may ultimately be the Great DAT Divide.
Not the divide between Bitcoin and Ethereum.
Not simply the divide between large treasury companies and small ones.
And not even the divide between those that survive this particular market cycle and those that do not.
The more durable divide may emerge between companies that remain dependent upon the value of what they accumulated and those that learn how to build something financially productive around it.
The first generation proved that corporations could accumulate digital assets at institutional scale.
The next will have to prove what those treasuries are actually for.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.