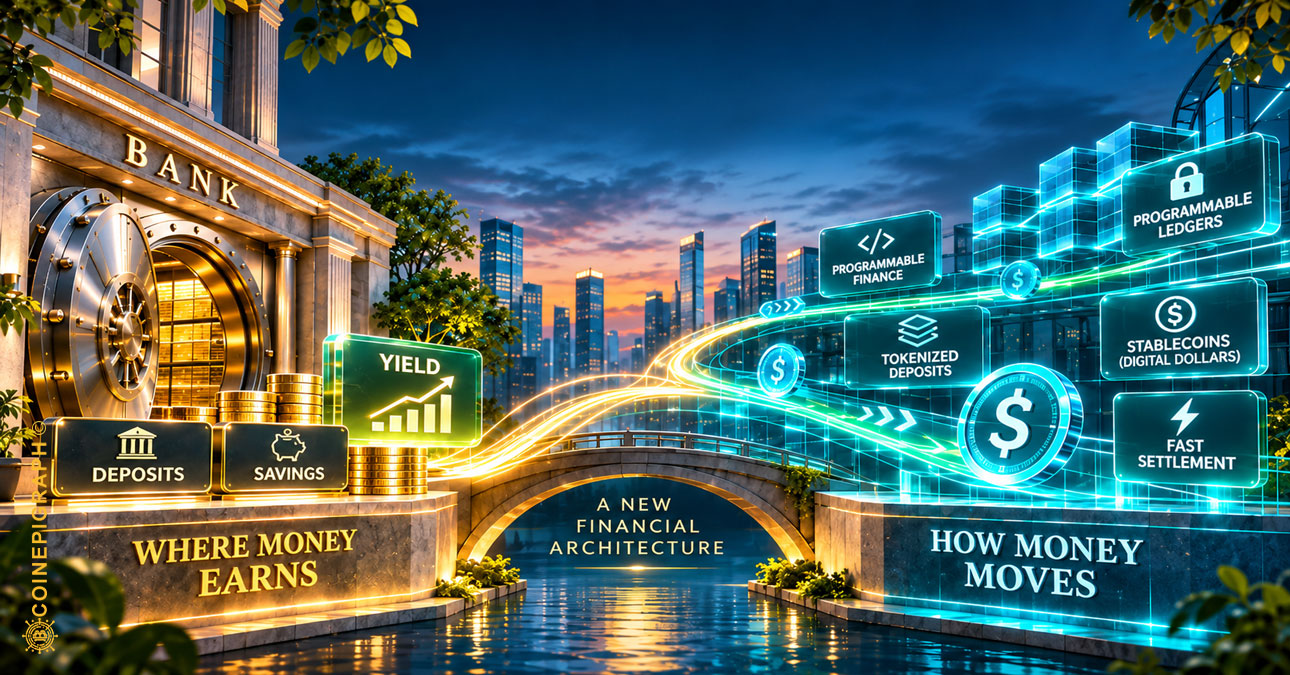
Banks spent years treating stablecoins as competitors to deposits. A new architecture suggests another possibility: deposits can remain where money earns while stablecoins, tokenized deposits and programmable ledgers increasingly determine how it moves.
By CoinEpigraph Editorial Desk
For most of modern banking, where money sits and how money moves have been closely connected.
A customer deposits dollars at a bank. The bank records the balance, pays whatever interest applies and provides the infrastructure through which those dollars can be spent or transferred. Checks gave way to cards, ACH and real-time payments, but the basic relationship remained recognizable. The deposit account was both a place to hold money and the starting point for moving it.
Digital money is beginning to loosen that connection.
SoFi recently introduced an unusually clear example. Its SoFi Earn product, or SOFIE, is a tokenized bank deposit. Each unit represents a dollar held at SoFi Bank, earns interest and is eligible for FDIC insurance subject to applicable limits. But SOFIE itself is not the stablecoin SoFi designed for blockchain payments.
When a customer wants to move that value onchain, SOFIE can be converted one-for-one into SoFiUSD.
The distinction is simple enough to disappear inside an app.
It is considerably more important underneath it.
One instrument is designed primarily to hold money and earn. Another is designed to move it.
That separation may point toward a larger restructuring of banking than the question of whether stablecoins replace deposits.
The Deposit Does Not Have to Travel
Stablecoins originally presented banks with an awkward proposition.
Customers could move dollar-denominated value around the clock without waiting for traditional banking hours or conventional payment systems. The tokens could cross blockchain networks, enter exchanges, settle transactions and move between wallets without requiring every transfer to pass through the familiar bank-payment architecture.
But a dollar leaving a deposit for a stablecoin can also represent funding leaving the banking system.
That matters because deposits are not simply balances displayed on banking applications. They are liabilities of banks and an important source of funding for lending and other financial activity.
Recent research from the Bank for International Settlements provides evidence that deposits and stablecoins can compete for the same money. Researchers examining U.S. data found that increases in bank deposit rates were followed by slower growth in reserve-backed stablecoins. The relationship suggests that at least some users make an economic choice between keeping dollars in deposits and holding them as stablecoins.
The emerging banking response is not necessarily to defeat that choice.
It may be to redesign it.
SoFi’s structure allows the deposit relationship to remain intact while the money is being held. The customer receives the economics and protections associated with the deposit. Only when the customer wants the characteristics of blockchain money does the value move into the stablecoin.
The bank therefore does not need to make the stablecoin perform every monetary function.
It can let the deposit do one job and the stablecoin another.
Banks Are Beginning to Build Around the Distinction
The same principle is appearing elsewhere, although in different forms.
Cross River Bank recently integrated Ripple’s RLUSD stablecoin into its core banking infrastructure. Businesses using the platform can access dollars, RLUSD, ACH, wires and real-time payments through the same banking environment.
Cross River does not need to persuade every customer to abandon traditional dollars for RLUSD. Instead, RLUSD becomes another available payment rail.
That distinction changes the competitive question.
A bank no longer has to decide whether the future is ACH, real-time payments or blockchain settlement. Its infrastructure can increasingly choose among them according to what a transaction requires.
Google Cloud Universal Ledger is approaching the problem from another direction.
In a recent Swiss pilot, participating institutions used tokenized commercial-bank money to support immediate transfers between customers while allowing the obligations between banks to be settled later. Rather than requiring every customer transaction to trigger an equally immediate movement of liquidity between institutions, payments could accumulate, offset one another and periodically settle the remaining difference.
Customers could experience fast movement while banks conserved liquidity.
This is not merely blockchain being substituted for an existing database. It begins to separate the experience of transferring money from the institutional process required to settle the obligations created by those transfers.
Jack Henry’s planned integration with Google Cloud Universal Ledger extends that idea toward community and regional financial institutions. Its stated objectives include helping banks offer tokenized deposits while preserving their deposit relationships and improving capital efficiency through clearing and netting.
The pieces are different, but they are moving in a similar direction.
Money does not necessarily have to exist in the same form while it is being held, transferred and ultimately settled.
The Payment Rail Is Becoming a Choice
This becomes more significant when payment networks begin accommodating the same architecture.
Mastercard and SoFi have been working to make SoFiUSD available as a settlement option across Mastercard’s network. Mastercard’s Multi-Token Network is also intended to support interoperability among conventional fiat money, stablecoins and tokenized deposits.
The importance is not that Mastercard suddenly becomes a blockchain company.
It is that a global payment network can increasingly become less concerned with insisting upon a single form of settlement money.
For decades, payment systems largely hid their complexity from consumers. A card swipe might look instantaneous at the checkout counter even though authorization, clearing and final settlement occurred through different systems and at different times.
Digital money adds another layer to that abstraction.
A future transaction might begin with a customer holding an interest-bearing bank deposit. Value could be represented digitally for transfer, cross a programmable network and eventually create a settlement obligation between financial institutions. The customer may see little more than a balance changing on a screen.
The machinery underneath could involve several forms of money.
That is a different vision from the early stablecoin narrative, which often assumed that a superior digital dollar would eventually displace slower forms of money.
The financial system may instead be becoming more modular.
Banks Have a Reason to Keep the Deposit
This architecture also helps explain why tokenized deposits are receiving more institutional attention.
Banks have little incentive to surrender deposits unnecessarily.
A stablecoin can provide attractive payment characteristics, but if customers permanently move large balances from bank deposits into reserve-backed tokens, the composition of financial-system funding changes with them. Banks potentially lose deposits while stablecoin issuers accumulate reserves, often in cash and short-term government securities.
The issue is larger than which digital dollar consumers prefer.
It concerns where funding resides.
Tokenized deposits offer banks another path. They can provide programmability and faster movement while remaining liabilities of the issuing commercial bank. Stablecoins can then be used where their particular characteristics—interoperability, blockchain settlement, portability or continuous availability—are useful.
The two instruments do not necessarily have to eliminate one another.
They can become different layers of the same financial architecture.
That possibility complicates the familiar argument that stablecoins will either replace banks or be absorbed by them. Banks may instead incorporate stablecoin rails while protecting the economic function of deposits.
The competition would then move somewhere else.
It would become a contest over which institution controls the interface, which ledger records the obligation, which network transports value, which asset provides liquidity and which entity ultimately retains the customer relationship.
Money Is Becoming Modular
Banking has already separated financial functions many times.
A consumer can hold money at one institution, pay through a card network operated by another company, send funds through a third-party application and ultimately settle through infrastructure the customer never sees.
Tokenization pushes that separation deeper into the money itself.
The asset that earns does not necessarily have to be the asset that travels.
The representation that travels does not necessarily have to be the instrument in which the final obligation is settled.
And the network carrying the transaction does not necessarily need to own the customer deposit behind it.
That creates opportunities, but also new dependencies. Conversion between different forms of money must remain reliable. Liquidity has to be available when customers want to move between them. Deposit insurance applies differently from stablecoin protections. Settlement networks introduce their own operational and counter-party risks. A seamless interface can obscure meaningful legal differences between the instruments operating beneath it.
Those distinctions will matter more as the architecture becomes easier to use.
The most successful systems may ultimately be the ones in which customers barely notice them.
The Bank May Remain Even When the Rail Changes
Stablecoins initially demonstrated something traditional finance could not ignore: dollars could move continuously across programmable networks without waiting for the banking system’s conventional operating model.
Banks are now responding in a way that is more sophisticated than simply issuing their own tokens.
They are beginning to decide which functions should remain attached to the deposit and which can migrate to new infrastructure.
SoFi provides the clearest consumer example so far. Money can remain in a tokenized bank deposit while it earns, then become a stablecoin when the customer wants to move it. Cross River shows how a bank can incorporate an outside stablecoin as another rail. Google Cloud and Jack Henry are exploring how commercial-bank money itself can move through shared programmable infrastructure without requiring banks to abandon their deposit relationships.
None of these models has yet established the final architecture of digital banking.
But together they suggest that the dividing line may not ultimately be between traditional money and digital money.
It may be between the different jobs money performs.
Banks spent much of the stablecoin era asking whether deposits would leave the banking system for blockchain networks. A different possibility is beginning to emerge.
The deposit can stay.
The rail can change.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.