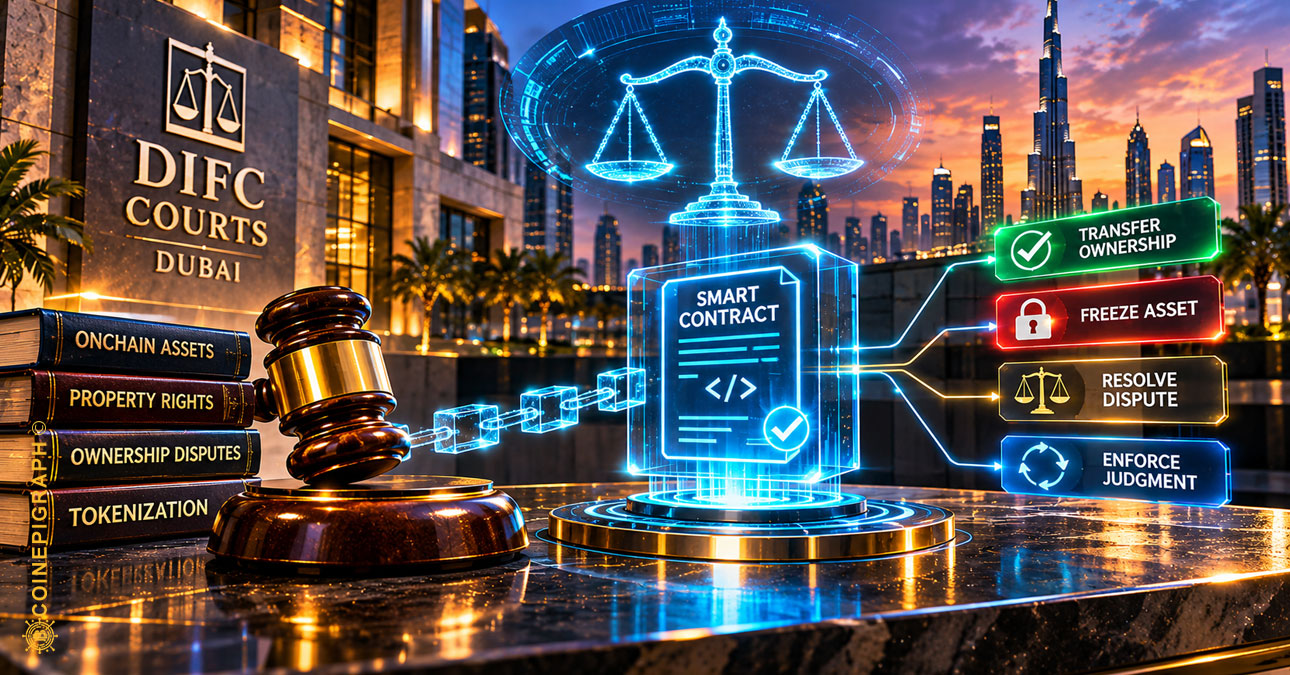
Dubai’s DIFC Courts are proposing a way for courts and other dispute forums to communicate legally authorized decisions to smart contracts. The idea exposes a problem institutional tokenization can no longer avoid: putting property on-chain also means deciding what happens when ownership becomes disputed.
By CoinEpigraph Editorial Desk
Blockchains are very good at following instructions.
That becomes more complicated when the instructions themselves are disputed.
A token can move from one wallet to another exactly as its smart contract permits. Collateral can be released when programmed conditions are satisfied. Ownership can be recorded with precision, transactions can settle without waiting for a traditional transfer agent, and the ledger can preserve an enduring record of what happened.
None of that necessarily determines what should happen after fraud, a contractual breach, an erroneous transfer or a legitimate disagreement over who owns the asset.
Dubai International Financial Centre Courts is now proposing that the legal system become more directly connected to that problem.
On November 5, DIFC Courts and its collaborators published The Dispute Resolution Oracle: Foundations of a Decentralised Jurisdiction, a white paper proposing an open framework connecting blockchain-based smart contracts with courts and other qualifying dispute-resolution forums.
The important word is connecting.
The proposal does not establish that a Dubai court can reach into Bitcoin, Ethereum or another public blockchain and reverse whatever transaction it chooses. Nor does it demonstrate judicial control over arbitrary self-custodied assets.
Instead, the proposed Dispute Resolution Oracle, or DRO, is opt-in. Parties and applications would agree beforehand that a particular court or other qualifying forum can resolve certain disputes. The surrounding smart-contract architecture would then be capable of recognizing the resulting authorized decision.
That is a narrower proposition than courts controlling blockchains.
For institutional finance, it may also be a more consequential one.
The Problem Begins When the Code Works
Much of blockchain’s financial appeal comes from deterministic execution.
If specified conditions are satisfied, the system executes. Participants do not necessarily need an intermediary to decide whether the transaction should proceed.
Financial institutions, however, operate in a world where the legitimacy of a transaction and its technical validity are not always the same thing.
A private key can authorize a transfer that was induced by fraud. An administrator can possess legitimate system privileges and use them improperly. Two parties can interpret a contractual obligation differently. Assets can become subject to insolvency proceedings. Ownership can be challenged after death. Collateral can become part of litigation.
In those situations, the blockchain may have an accurate record of what happened without providing an answer to what the law says should happen next.
That distinction becomes increasingly important as tokenization moves beyond cryptocurrency and into securities, funds, bonds, collateral and other forms of institutional property.
The question is no longer simply whether financial assets can exist on-chain.
It is whether the legal rights surrounding those assets can operate there as well.
DIFC Has Been Moving Toward the Problem
The Dispute Resolution Oracle did not appear in isolation.
In December 2025, DIFC Courts announced that specialized digital-asset cases could use third-party custody and blockchain intelligence services. Zodia Custody was selected to provide optional neutral custody for disputed digital assets during proceedings, while Crystal Intelligence was brought in to provide tracing, monitoring and investigative capabilities.
The significance was practical. A court dealing with digital property needs more than legal doctrine. It may need to identify assets, follow their movement and prevent disputed property from disappearing while a case proceeds.
A second development followed in October.
DIFC Courts began issuing court orders and hearing records with blockchain-verifiable credentials using Avalanche C-Chain. A cryptographic fingerprint of the document is associated with a nontransferable credential recorded on the blockchain, allowing a recipient to verify that the document was issued by DIFC Courts and has not subsequently been altered.
The underlying document and confidential case information remain off-chain.
That system addresses authentication. It does not make the judgment self-executing.
The Dispute Resolution Oracle moves the discussion one step further by asking whether the outcome of a recognized dispute-resolution process can become actionable within participating blockchain infrastructure.
The Court Does Not Have to Control the Blockchain
That distinction matters.
The most provocative interpretation of the proposal would be that courts are preparing to override decentralized networks. The available framework does not establish that.
Its power instead appears to depend upon architecture and consent.
A smart contract or tokenized financial system would have to be designed to recognize the dispute-resolution mechanism. Parties could select an appropriate forum before transacting. If a qualifying dispute later arose, the framework contemplates preserving the disputed asset while the matter is considered and ultimately allowing a final decision to be reflected through the participating on-chain system.
The human decision does not disappear.
DIFC’s description specifically contemplates judges, arbitrators, mediators and experts continuing to operate off-chain. The proposed oracle provides an interface between their decisions and programmable infrastructure.
That changes the decentralization question.
A blockchain can remain decentralized at the network level while a financial instrument operating on it contains rules specifying how legal intervention occurs.
The distinction already exists elsewhere in finance. Securities operate within markets whose trading and settlement infrastructure may be highly automated, but legal ownership remains surrounded by rules for bankruptcy, fraud, inheritance, contractual disputes and judicial orders.
Tokenization does not make those circumstances disappear.
It forces financial architects to decide whether the remedies will remain entirely outside the technology or become part of its design.
Immutability Meets Due Process
That creates a difficult engineering problem because legal systems and blockchains approach finality differently.
Blockchains generally prize predictable execution and resistance to arbitrary alteration.
Courts deliberately permit interruption.
Judgments can be challenged. Orders can be stayed. Evidence can change the understanding of a dispute. Jurisdiction itself can be contested. Appellate courts exist because a legally authorized decision may still be reversed.
The DRO framework acknowledges some of that tension. Its public description includes limited asset freezes, early review, reasoned decisions and appeal rights.
Those safeguards are not secondary details.
They determine whether connecting judicial authority to programmable assets becomes credible infrastructure or simply creates another privileged control point.
Consider a tokenized security frozen because ownership is disputed. A technical system must know who can initiate that freeze, how the instruction is authenticated, how long it remains effective and what happens if a higher authority later changes the underlying decision.
The difficult part is not teaching software to execute an instruction.
It is determining which instruction deserves to be executed.
Institutional Tokenization Needs Exception Handling
This may ultimately be where the proposal matters most.
Financial tokenization has spent years demonstrating that assets can be represented, transferred and settled using distributed ledgers. Institutional adoption introduces another requirement: investors must know that their legal rights survive the transition.
A $100 million tokenized bond cannot depend entirely upon the assumption that every transfer, contractual interpretation and administrative action will proceed without dispute.
Neither can a tokenized fund, private-market security or collateral arrangement.
Institutions therefore face a choice. They can keep dispute resolution largely outside blockchain infrastructure and attempt to enforce legal outcomes afterward, or they can design financial instruments that recognize specified legal authority from the beginning.
The DRO explores the latter.
It is being presented as an open standard rather than a mechanism restricted exclusively to DIFC Courts. If that principle survives implementation, the larger idea would not necessarily be one court exercising authority across global blockchains. Different transactions could recognize different courts, arbitration systems or qualifying forums while using a common technical framework for communicating legitimate decisions.
That raises another set of questions.
What happens when jurisdictions disagree? Which forums qualify? Who controls the oracle infrastructure? What prevents fraudulent instructions? Which assets remain beyond its reach? And how much administrative control can be introduced before a supposedly decentralized financial instrument begins to resemble conventional finance running on a different ledger?
The white paper begins that discussion. It does not settle it.
The Legal Layer Is Moving Closer to the Asset
The institutional significance of the Dispute Resolution Oracle is therefore not that Dubai has found a way to make blockchains obey judges.
It has not demonstrated that.
The more important development is that a major financial jurisdiction is treating dispute resolution as something that may need to be designed into tokenized financial infrastructure itself.
That marks a different stage in the evolution of tokenization.
The first challenge was proving that an asset could exist on-chain.
The next was determining what an investor legally owns when it does.
Now another question is arriving: what happens when the legal owner and the blockchain disagree?
For institutional finance, the answer cannot simply be that the code already executed.
Property rights matter most when somebody contests them.
If tokenized markets are going to carry increasingly valuable financial assets, the infrastructure surrounding those markets will eventually have to accommodate the messy circumstances that deterministic software was designed to avoid.
DIFC’s proposal suggests one possible route.
The blockchain may continue to determine what the code permits.
The harder question is who gets to determine what happens when the law says the code produced the wrong result.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.