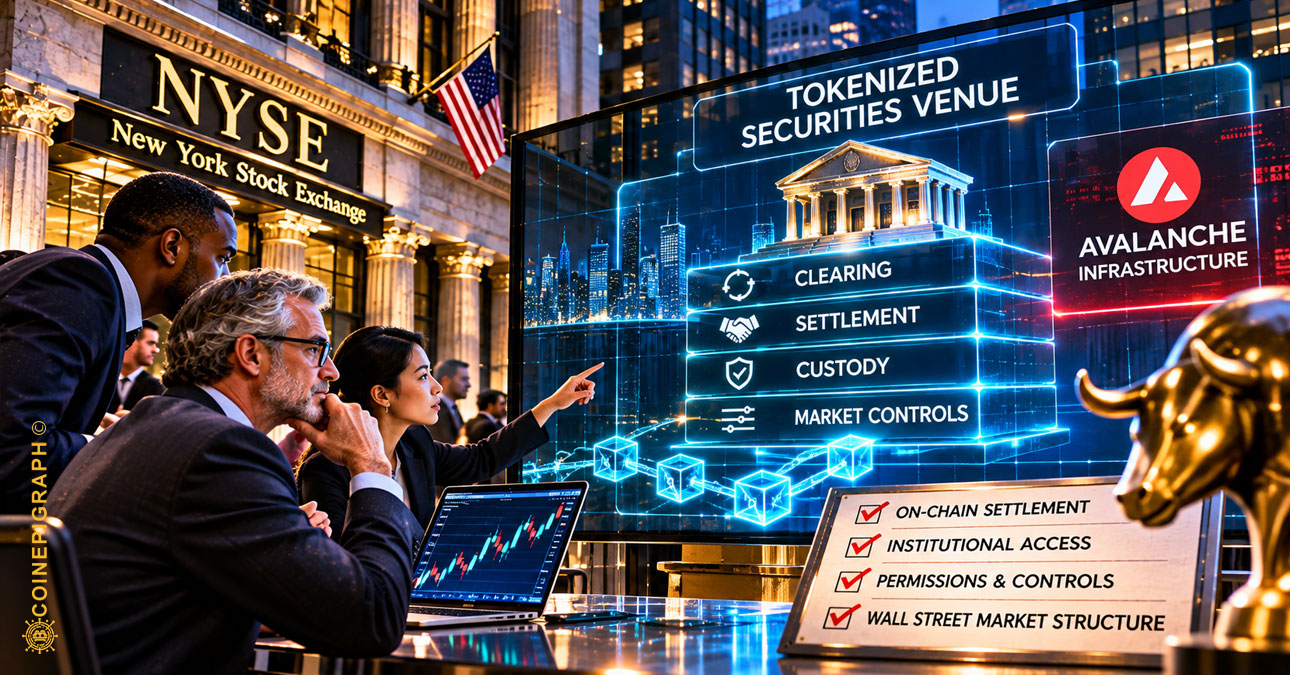
NYSE’s decision to use Avalanche technology for the clearing and settlement infrastructure behind its forthcoming tokenized-securities venue reveals something larger than another institutional blockchain partnership. Wall Street appears increasingly interested in blockchain without surrendering the market structures, permissions and controls it already understands.
By CoinEpigraph Editorial Desk
For years, one of the central promises of tokenization was that traditional financial assets would eventually move onto blockchains.
That is beginning to happen.
Just not quite in the way the original thesis imagined.
The New York Stock Exchange said Monday that its affiliated forthcoming digital alternative trading system will use Avalanche as the blockchain supporting its clearing infrastructure. The platform is being designed for around-the-clock trading, clearing and settlement of tokenized securities, subject to regulatory approval.
The announcement is significant for Avalanche. But the more consequential part of the story may be what NYSE is not changing.
NYSE’s Pillar technology remains at the center of trading. Regulated transfer agents remain involved. Issuer rights and corporate actions remain. Participation can be controlled. The venue is being developed within the existing regulatory system rather than outside it.
Blockchain enters underneath much of that structure.
It changes the ledger.
It changes settlement.
It does not require Wall Street to stop being Wall Street.
The Market Comes to the Technology
NYSE has been showing its hand for most of this year.
In February, executives described a prototype combining Pillar, the matching technology used across NYSE markets, with a privately permissioned blockchain capable of atomic settlement. The objective was not to force traditional market participants into an unfamiliar trading environment. NYSE said it wanted the experience to remain as consistent as possible with the infrastructure those participants already use.
The blockchain provider had not yet been publicly identified.
Now it has.
Avalanche will provide the core ledger technology to the clearing firm supporting the forthcoming NYSE-affiliated venue. NYSE says the ledger needed to be fast and reliable, offer predictable costs, support a large developer community and allow the exchange to control who can participate.
That last requirement deserves attention.
Public blockchains were originally compelling in part because participation did not depend upon an institution deciding who belonged on the network. NYSE is approaching the technology from almost the opposite direction.
It wants some of blockchain’s properties without abandoning institutional permission.
That is not a contradiction.
It may be the architecture regulated finance actually needs.
Tokenization Is Splitting Into Different Models
The phrase tokenized stock increasingly describes several different things.
A token can represent economic exposure to a security without placing the investor directly onto the issuer’s shareholder register. Another structure can place an underlying share inside a special-purpose vehicle or custody arrangement and issue a token representing an interest in it.
Then there are issuer-sponsored securities in which tokenization becomes part of the company’s recognized ownership and transfer infrastructure.
Those distinctions have become increasingly important as public companies question tokenized versions of their shares created without their participation.
NYSE is building toward a different model.
Its network of tokenization and transfer-agent partners now includes Securitize, tZERO, Broadridge, Computershare, Equiniti and Superstate. Computershare, Equiniti and Broadridge together serve close to 5,000 publicly listed companies, according to NYSE, including nearly 99% of the S&P 500.
That is not the infrastructure of a parallel market trying to route around issuers.
It is an attempt to bring issuers, transfer agents, broker-dealers, trading technology and blockchain settlement into the same market structure.
The distinction suggests that the institutional argument over tokenization may have been framed too narrowly.
The question is not merely whether stocks will be tokenized.
It is increasingly who controls the tokenization architecture.
Avalanche Won a Layer, Not the Entire Market
That distinction also matters when considering what NYSE’s selection means for Avalanche.
The forthcoming digital venue will support equities listed on a range of blockchains. Avalanche has been selected as the core ledger technology for the clearing firm that records and settles trades.
Those are not the same thing.
A security originating on another supported blockchain could potentially enter a market whose trading technology remains NYSE Pillar while the clearing and settlement ledger uses Avalanche infrastructure.
That makes the architecture more modular than the familiar idea that one blockchain must become the home of an entire financial market.
Trading can occupy one layer.
Issuance can occupy another.
Transfer agents can maintain legally significant ownership records.
Settlement can use distributed ledger technology.
Custody can remain another function entirely.
The significance of Avalanche’s selection is therefore not that NYSE has decided to move its market wholesale onto a crypto network.
It is that blockchain technology has won a defined job inside a regulated market architecture.
The Ledger Is Where the Experiment Gets Interesting
Settlement has long been one of blockchain’s more credible institutional use cases.
Traditional securities markets separate the trade from its final settlement. Clearing, netting, custody and recordkeeping developed over decades to make that system reliable at enormous scale.
Distributed ledgers offer a different possibility.
Assets and payment can potentially move together, allowing a transaction to settle atomically rather than creating separate obligations that must later be reconciled.
NYSE is attempting to combine that capability with an established exchange environment.
If it works at scale, tokenization could begin changing more than the representation of the asset.
It could change the mechanics underneath the market.
Around-the-clock trading becomes more plausible when settlement infrastructure is not tied as tightly to traditional operating windows. Stablecoin funding could allow cash legs to move alongside tokenized securities. Ownership records could update closer to the transaction itself.
None of this means the surrounding institutions disappear.
In NYSE’s design, they become part of the new architecture.
Wall Street Wants Control
This may explain why institutional blockchain adoption has sometimes looked slower than crypto expected.
The obstacle was not necessarily that large financial institutions failed to understand blockchain.
They may have been waiting for architectures that allowed them to use it without surrendering the controls their businesses require.
A securities market must know more than whether a transaction is technically valid.
It must know who may participate. It must preserve shareholder rights. It must process dividends and corporate actions. It must satisfy securities laws, sanctions requirements and supervisory obligations. Someone must maintain authoritative records. Someone must be accountable when something fails.
A general-purpose public blockchain does not answer all of those questions by itself.
NYSE’s approach suggests that institutions may increasingly treat blockchain the way they treated other foundational technologies: adopt the useful properties, surround them with institutional controls and integrate them into systems already responsible for enormous amounts of capital.
That is a very different proposition from replacing the financial system.
It is modernization from inside it.
Public Chains Are Not Necessarily Shut Out
There is another reason not to mistake NYSE’s architecture for the only model that can emerge.
On the same day as the Avalanche announcement, Formation Securities notified the SEC of its intention to operate a tokenized-securities venue on Solana, a public permissionless blockchain. Its proposed structure would still restrict participation to verified investors and preserve shareholder rights while allowing tokenized securities to trade through permissioned liquidity pools.
Elsewhere, tokenized U.S. equities have already begun trading under the SEC’s Innovation Exemption using infrastructure built on Canton.
Several architectures are therefore developing at once.
One begins with established market infrastructure and inserts blockchain into selected layers.
Another begins with public blockchain infrastructure and adds the permissions necessary for regulated securities.
Others may use institutional distributed ledgers that bear little resemblance to the public crypto markets familiar to retail investors.
The eventual market may contain all three.
That makes the competition larger than Avalanche versus Solana versus Canton.
The real contest is over which architecture can satisfy issuers, investors, intermediaries and regulators while improving something meaningful about the existing market.
Adoption Is Not the Same as Token Value
There is also a distinction investors should resist overlooking.
A blockchain can become useful financial infrastructure without every dollar of activity flowing through it becoming equivalent economic value for the network’s native token.
The relevant questions are more specific.
What operations require the token? What fees are generated? Who receives them? Does activity create sustained demand for network resources? Can institutional users operate purpose-built environments without creating material demand in the public token market?
Those questions cannot be answered merely by pointing to the size of the assets that might eventually be tokenized.
Infrastructure adoption and token value capture are different mechanisms.
NYSE’s decision is evidence that Avalanche technology can compete for an important role in institutional market infrastructure.
It is not, by itself, a valuation model for AVAX.
What Wall Street Actually Wanted
For much of crypto’s history, institutional adoption was imagined as a migration.
Eventually, the thinking went, stocks, bonds and other financial assets would move onchain and traditional finance would have to adapt to the architecture it found there.
NYSE is showing another path.
The market does not necessarily migrate.
The technology comes to the market.
The matching engine can remain. The transfer agent can remain. The issuer can remain in control of its securities. Regulatory oversight can remain. Existing financial institutions can retain their roles while the ledger underneath them changes.
That may sound less revolutionary than replacing Wall Street.
It could prove considerably more consequential.
Financial infrastructure rarely changes because every institution agrees to abandon the old system at once. New technology usually enters where it solves a particular problem, proves itself, and gradually becomes difficult to distinguish from the infrastructure around it.
NYSE has now identified one of those places.
It is the ledger beneath the market.
Wall Street may not be moving onto crypto’s financial system.
It may be taking blockchain technology and rebuilding parts of its own.
At CoinEpigraph, we are committed to delivering digital-asset journalism with clarity, accuracy, and uncompromising integrity. Our editorial team works daily to provide readers with reliable, insight-driven coverage across an ever-shifting crypto and macro-financial landscape. As we continue to broaden our reporting and introduce new sections and in-depth op-eds, our mission remains unchanged: to be your trusted, authoritative source for the world of crypto and emerging finance.
— Ian Mayzberg, Editor-in-Chief
The team at CoinEpigraph.com is committed to independent analysis and a clear view of the evolving digital asset order.
To help sustain our work and editorial independence, we would appreciate your support of any amount of the tokens listed below. Support independent journalism:
BTC: 3NM7AAdxxaJ7jUhZ2nyfgcheWkrquvCzRm
SOL: HxeMhsyDvdv9dqEoBPpFtR46iVfbjrAicBDDjtEvJp7n
ETH: 0x3ab8bdce82439a73ca808a160ef94623275b5c0a
XRP: rLHzPsX6oXkzU2qL12kHCH8G8cnZv1rBJh TAG – 1068637374
SUI – 0xb21b61330caaa90dedc68b866c48abbf5c61b84644c45beea6a424b54f162d0c
and through our Support Page.
🔍 Disclaimer: CoinEpigraph is for entertainment and information, not investment advice. Markets are volatile — always conduct your own research.
COINEPIGRAPH™ does not offer investment advice. Always conduct thorough research before making any market decisions regarding cryptocurrency or other asset classes. Past performance is not a reliable indicator of future outcomes. All rights reserved | 版权所有 ™ © 2024-2029.